Mortgage refinance eligibility in Australia depends on more than whether you have made repayments on time or found a loan with a lower advertised rate. When you apply to refinance, lenders generally reassess your financial position, the property securing the loan and whether the new loan appears affordable under their lending criteria.
This article explains the common factors lenders may consider when assessing a refinance application. It is general information only and does not take into account your personal objectives, financial situation or needs. Eligibility, pricing and approval outcomes depend on your circumstances and the lender’s assessment criteria.
What does refinance eligibility mean?
Refinancing means replacing your current home loan with a new loan, either with your existing lender or a different lender. The new loan may have a different interest rate, repayment type, loan term, lender, features or borrowing amount.
Eligibility is the lender’s assessment of whether you meet its requirements for the new loan. Even if you qualified for your original mortgage, a lender will usually assess your current position again. This is because your income, expenses, property value, equity, debts and credit profile may have changed since you first borrowed.
Refinancing may be considered for many reasons, including seeking a different interest rate, changing loan features, adjusting the loan term, consolidating debts or accessing equity. The reason for refinancing can influence the level of assessment and the information a lender asks you to provide.
Key factors lenders commonly assess
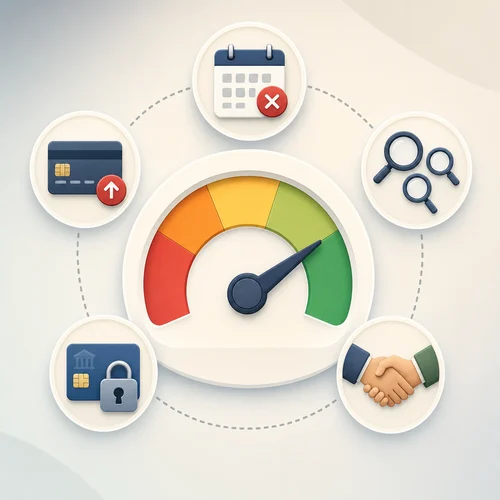
Lenders do not all use the same assessment approach, but most refinance applications involve similar core checks. The following table summarises the some areas commonly reviewed.
| Assessment factor | Why it may matter | What you can prepare |
|---|---|---|
| Income and employment | Lenders look at whether your income appears stable and sufficient to support repayments. | Recent payslips, tax documents, employment details or business financials if self-employed. |
| Expenses and debts | Living costs, credit cards, personal loans, car loans and other commitments affect serviceability. | Bank statements, loan statements and a realistic summary of regular expenses. |
| Loan-to-value ratio | The amount you want to borrow compared with the property value affects risk and available loan options. | Current loan balance, property details and an understanding that valuation outcomes can vary. |
| Credit history | Repayment conduct and credit enquiries can influence how a lender views the application. | Review your credit report and address errors or unresolved issues where possible. |
| Property and valuation | The property is security for the loan, so lenders may assess its value, condition, location and marketability. | Property address, ownership details and information about major changes or improvements. |
| Loan purpose | Refinancing for a lower rate may be assessed differently from debt consolidation or accessing equity. | A clear explanation of why you want to refinance and how the funds will be used, if borrowing more. |
Income, employment and home loan serviceability
Home loan serviceability refers to a lender’s assessment of whether you appear able to afford the proposed loan repayments. This is one of the most important parts of refinance approval criteria.
Lenders commonly review your income sources, such as salary, wages, self-employed income, rental income, overtime, bonuses or other regular income. They may treat different types of income differently. For example, a lender may want to see a longer history for variable income, contractor income or business income than for a permanent salary.
Employment stability can also be relevant. A recent job change, probationary period, casual work arrangement, reduced hours or a move to self-employment may lead to additional questions. This does not automatically prevent refinancing, but it may affect the lender’s assessment or the documents requested.
Expenses and commitments are assessed alongside income
Income alone does not determine eligibility. Lenders also consider your regular expenses and existing financial commitments. These may include:
- credit card limits, even if you do not use the full limit;
- personal loans, car loans and buy now pay later arrangements;
- existing investment property loans or other mortgages;
- child support or other regular obligations;
- general living expenses, including household costs, transport, insurance and education expenses; and
- dependants and household structure.
Before applying, it can be useful to review your budget and identify ongoing commitments that may affect serviceability. Reducing unused credit limits or paying down unsecured debt may be worth discussing with a lender or broker, but the right approach depends on your circumstances.
Loan-to-value ratio and available equity
The loan-to-value ratio, often called LVR, compares the loan amount to the property’s assessed value. For example, if the loan amount is high compared with the property value, the LVR is also high. A lower LVR generally means you have more equity in the property, while a higher LVR may limit loan options or affect the cost and conditions of borrowing.
LVR is important because the property acts as security for the loan. Lenders usually want confidence that the property value supports the amount being borrowed. If you are refinancing without increasing your loan amount, LVR may still matter because the lender will consider the current value of the property, not just the value when you first bought it.
If you want to borrow more than your current loan balance, such as to consolidate debt, renovate or access equity, the requested loan amount may increase your LVR. This can change the lender’s assessment and may affect whether lenders mortgage insurance, a different product type or extra conditions are relevant.
Property valuation can affect the outcome
A lender may arrange a valuation or use another valuation method as part of the refinance assessment. The result may be different from an online estimate, real estate appraisal or your own expectation of market value.
If the valuation is lower than expected, your LVR may be higher than anticipated. This could affect available refinance options, the amount you can borrow, or the overall cost of refinancing. Because valuation methods and lender policies vary, it is sensible to treat property value estimates as indicative until a lender completes its assessment.
Credit score, repayment history and account conduct
Your credit history may influence a refinance application. Lenders may review your credit report, recent credit enquiries, existing debts and repayment conduct. They may also look at how you have managed your current home loan and other accounts.
A strong history of making repayments on time may support an application, while missed repayments, defaults, hardship arrangements, frequent credit applications or high unsecured debt levels may lead to closer review. Different lenders may assess credit events differently, and timeframes or severity can matter.
Before applying, consider checking your credit report for errors or unfamiliar enquiries. If something is incorrect, you may be able to request a correction through the relevant credit reporting process. If you have had repayment difficulties, it may be useful to be ready to explain the circumstances and provide evidence of your current position.
Documents commonly requested for refinance applications
Having the right refinance documents ready can make the process more efficient. Requirements vary by lender and borrower type, but commonly requested documents include:
- proof of identity;
- recent payslips or employment income evidence;
- tax returns, financial statements or accountant information for self-employed borrowers;
- bank statements showing income and expenses;
- current home loan statements;
- credit card, personal loan or car loan statements;
- rates notices or property details;
- rental income evidence, if relevant; and
- details of the purpose of any additional borrowing.
Incomplete or inconsistent documents can slow down an application. Check that names, addresses, loan balances and income details are accurate and up to date before submission.
How your refinance purpose can change the assessment
Lenders may ask why you want to refinance. Your purpose helps them understand the structure and risk of the proposed loan.
Common refinance purposes include:
- seeking a different rate or loan features: such as an offset account, redraw facility, fixed rate, variable rate or split loan;
- changing the loan term: for example, shortening the term or extending it to reduce repayments, noting that a longer term may increase total interest over time;
- consolidating debts: rolling other debts into the home loan may reduce the number of repayments, but it can increase total interest if short-term debts are repaid over a longer mortgage term;
- accessing equity: borrowing additional funds for renovations, investment or other purposes may require extra assessment; and
- switching lenders: moving to a different lender may involve a full application, valuation and discharge process.
If you are comparing potential refinance outcomes, a mortgage refinancing calculator can help you model repayments and broad scenarios. Calculator results are estimates only and should be checked against actual lender offers, fees and loan terms.
Preparing before you apply
Preparation does not guarantee approval, but it may help you understand your position and reduce avoidable delays. A practical preparation process may include the following steps.
- Clarify your goal. Decide whether you are refinancing for rate, flexibility, debt consolidation, equity access, term changes or another purpose.
- Review your current loan. Check your balance, repayment type, interest rate, package fees, fixed-rate period, offset balance and any discharge or break costs that may apply.
- Check your budget. Review your income, household expenses and existing debts before requesting a new loan amount.
- Estimate your equity. Compare your approximate property value with your current loan balance, while remembering that the lender’s valuation may differ.
- Review your credit report. Look for errors, missed payments or recent enquiries that may need attention.
- Gather documents early. Having payslips, loan statements and bank statements ready may make it easier to respond to lender requests.
- Compare more than the interest rate. Consider fees, features, repayment flexibility, loan term and whether the structure fits your objective.
If you are still deciding whether refinancing is the right next step, our article on choosing the right lender for mortgage refinancing explains how lender types, loan features and comparison factors can differ.
When a mortgage broker may be useful
A mortgage broker may help you understand how different lenders could assess your circumstances. Brokers can compare loan options from the lenders they work with and may help identify what documents are likely to be required.
Using a broker does not guarantee eligibility or approval. Brokers also do not usually compare every lender in the market. It is still important to ask questions about the broker’s lender panel, commissions, fees, loan options and why a product is being suggested.
If you want to discuss your situation with a professional, you can learn more about the role of mortgage brokers and the types of questions to ask before proceeding.
Common issues that may affect refinance eligibility
Some issues do not necessarily rule out refinancing, but they may make the assessment more detailed or reduce the number of available options. These can include:
- a high loan-to-value ratio;
- recent missed repayments or hardship arrangements;
- irregular income or a recent change in employment;
- high credit card limits or multiple unsecured debts;
- property valuation lower than expected;
- borrowing additional funds without a clear purpose;
- limited documentation for self-employed income;
- recent major life changes, such as separation, parental leave or reduced working hours; and
- fixed-rate break costs or other switching costs that reduce the benefit of refinancing.
If one of these applies to you, it may be worth seeking guidance before lodging multiple applications. Repeated credit enquiries can appear on your credit report and may influence some lenders’ assessments.
Costs and risks to consider before refinancing
Eligibility is only one part of the refinancing decision. A refinance that is technically available may not necessarily be suitable for your goals or cost-effective after fees and loan structure are considered.
Potential costs and risks can include:
- application, settlement, valuation or discharge fees;
- fixed-rate break costs on your existing loan;
- lenders mortgage insurance if your LVR is high and it applies under the lender’s policy;
- package or ongoing account fees;
- extending the loan term and paying more interest over time;
- consolidating short-term debt into a longer-term home loan; and
- losing features from your existing loan that you still value.
Ask for a clear breakdown of the costs of leaving your current loan and setting up the new one. You can then compare those costs with the potential repayment change, features and longer-term impact of the new loan.
Questions to ask before submitting a refinance application
Before applying, consider asking the lender or broker questions such as:
- What income documents will you need for my situation?
- How will my existing debts and credit card limits be assessed?
- Will a property valuation be required, and what happens if it is lower than expected?
- What is the estimated loan-to-value ratio based on the proposed loan amount?
- What fees, discharge costs or break costs should I consider?
- Will the new loan term increase or reduce the total interest I may pay?
- What features would I gain or lose compared with my current loan?
- Are there any conditions I should meet before applying?
In Conclusion
Understanding mortgage refinance eligibility in Australia can help you approach the process with clearer expectations. Lenders commonly assess serviceability, income, expenses, credit history, equity, LVR, property value, loan purpose and supporting documents.
Refinancing may provide benefits in some circumstances, but outcomes are not guaranteed and depend on lender criteria and your individual position. Taking time to review your finances, prepare documents and ask informed questions can help you decide whether to explore refinancing further.