
financialservicesonline
Income Insurance Calculator
| Bike Loans | JetSki Loans |
| Boat Loans | Mortgage Reduction |
| Business Loans | Personal Loans |
| Caravan Loans | Truck Loans |
| Short Term Cash | Debt Consolidation |
| Credit Cards | Home Loans |
| Car Loans |
:: finance :: Credit Cards
Stay informed with MoneyTips
Get practical financial information, news, guides and resources.
Credit Cards in Australia: Interest Rates, Fees & Features
Credit Cards Rates & Options
SHARE
Credit Cards Resources
Credit Cards Calculators
Related Articles

Chatbot
Q&A with
Paige Estritori
Which Credit Card is Right for You?
Credit cards differ in their interest rates, fees, rewards and promotional offers. Understanding how you spend and repay can help you compare their costs and features.
Start with what you can comfortably repay, then consider whether any incentives justify the card's costs.
How Do You Repay Your Balance?
Whether you pay your statement balance in full by the due date or carry a balance from month to month can make a substantial difference to the cost of a credit card.
If you usually repay in full, compare annual fees, interest-free conditions and the value of any rewards. If you carry a balance, pay particular attention to the purchase interest rate and ongoing fees. A low interest credit card may cost less than a rewards card, depending on your balance and repayments.
Use your typical balance and repayment amount when reviewing examples provided by card issuers. Paying only the minimum repayment can extend the time needed to clear a balance and increase total interest costs. Consider a credit limit that fits your budget rather than treating the limit as a spending target.
Compare Interest Rates and Balance Transfers
A card can have different interest rates for purchases, cash advances and balance transfers. Compare each rate that is relevant to how you expect to use the card, and check how repayments are allocated.
For a promotional balance transfer offer, check the introductory period, any transfer fee and the rate that applies to an unpaid transferred balance after the offer ends. Work out whether your budget allows you to repay the transferred amount within that period.
Also check how a balance transfer affects interest-free days on new purchases. A promotional transfer rate does not necessarily apply to other spending.
Understand Interest-Free Periods
Interest-free days generally apply to eligible purchases only when the card's repayment conditions are met. Check the amount you must pay by the due date to qualify, particularly if you have a balance transfer or another promotional balance.
An advertised maximum interest-free period is not available on every purchase. The time available depends on when the purchase falls in the statement cycle. Check the statement date, payment due date and card terms rather than assuming you always have the maximum number of days to pay.
Look at the Fees
Compare annual fees, cash advance fees, balance transfer fees, late payment fees and international transaction fees where applicable. A no annual fee credit card can still have other charges, so consider the total cost for your expected use.
ATM cash withdrawals using a credit card are generally treated as cash advances. A cash advance fee may apply, and interest generally starts from the transaction date rather than after an interest-free period. Overseas withdrawals may involve additional charges.
Check the current fee schedule and how charges are calculated before making a withdrawal or using the card overseas.
Weigh Up Cashback and Rewards
Some credit cards offer cashback or reward points on eligible spending. Compare the value you could realistically use with annual fees and any interest costs, rather than focusing only on a sign-up offer.
Interest and fees can outweigh cashback or rewards, especially if you carry a balance. Check eligible purchases, spending thresholds, points caps, expiry rules and redemption conditions. Avoid spending more than planned just to earn rewards.
Compare published rates, fees and conditions against your spending habits and repayment budget. Read the terms and conditions and seek clarification about anything you do not understand.
Share this product:
Finance Calculators

Our financial calculators are provided for your free use on this website and are designed to remove some of the guess-work to help you make more informed financial decisions.
Please note that some of our calculators may use assumptions that are not necessarily applicable to your current specific circumstances and we therefore cannot always guarantee their accuracy.
We recommend that you seek professional financial advice from a licensed professional before proceeding with a loan.
Loan Repayment and Finance Modeling Calculators
Fortnightly Mortgage Repayment Comparator
Compare the effect of paying monthly mortgage payments as opposed to paying fortnightly.
Bike Loan Calculator
Calculate and compare monthly repayments for a motorcycle loan at varying interest rates
Boat Loan Calculator
Calculate and compare monthly boat repayments for different loan values, deposit amount, etc
Business Loan Calculator
Calculate and compare monthly repayments at varying interest rates for a business loan
Business Equipment Lease Calculator
This calculator will help to calculate the lease finance repayments on new business plant and equipment.
Car Loan Calculator
Calculate and compare monthly car loan repayments with/without a deposit or trade-in
Car Lease Calculator
This calculator will help to calculate the lease finance repayments on a new car, including optional balloon/residual
Caravan Loan Calculator
Calculate and compare monthly caravan repayments
Caravan Commercial Hire Purchase Calculator
Calculate and compare monthly commercial hire purchase repayments on a caravan loan
Home Refinance Calculator
Compare the cost/benefits of refinancing your home loan.
Mortgage Repayments
Calculate monthly mortgage repayments on various home loan amounts and interest
rates.
Jetski Loan Calculator
Calculate and compare monthly jetski repayments
Personal Loan Calculator
Calculate and compare monthly repayments on a personal unsecured loan
Truck Loan Calculator
Calculate and compare monthly repayments on a truck loan
Truck Lease Calculator
This calculator will help to calculate the lease finance repayments on a new truck or commercial vehicle
Financial News & Information
Popular finance Articles
Related Articles
| How Credit Card Balance Transfers Can Damage Your Credit Rating Since the banks and finance providers have been castigated for the way they seemingly indiscriminately awarded credit to people who could ill afford it, the chances of being accepted for loans and credit cards have decreased. Concurrently, there is a greater focus on individual's being aware of how credit works and what their financial behaviors means in terms of a credit score and history. - read more
|
| Credit Card Secret Guarantee Most people use credit cards in some form or another but few truly appreciate one of the special features of credit cards that make using their credit card to insure their purchases. - read more
|
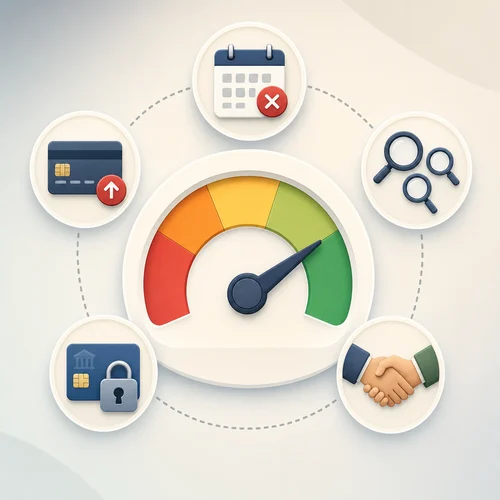
| 5 Credit Killers A good credit score speaks volumes about your financial habits. It's the evidence most creditors need to evaluate your credit worthiness. - read more
|
| 7 things you need to know about a Hire Purchase loan There are seven things you should know before you ever think of getting a Hire Purchase loan. Knowing these things will give you control and power in the loan process. Power and control will will save you money - read more
|
Recent finance Articles
Related Articles
| Business-purpose truck finance and borrower protections in Australia Business-purpose truck finance in Australia is often treated differently from consumer credit. This guide explains how National Credit Code coverage, business purpose declarations, broker conduct, contracts and borrower responsibilities may affect commercial truck finance protections. - read more
|
| Boat Insurance and Finance: What Borrowers Should Understand When a boat is financed, insurance can affect settlement, lender requirements and the borrower's financial risk if the vessel is damaged, stolen or written off. This guide explains why insurance may matter for secured boat finance in Australia and what borrowers should check before and after settlement. - read more
|
| What Happens If a Business Cannot Repay a Business Loan? Falling behind on a business loan can lead to arrears, fees, default action, enforcement against secured assets and potential claims under personal guarantees. This guide explains the main risks Australian business owners should understand and the practical steps to consider early. - read more
|
| Boat Loan Interest Rates and Comparison Rates Explained Boat loan interest rates, comparison rates and fees all affect the total cost of marine finance. This guide explains how advertised rates differ from comparison rates, what fees may be included or excluded, and why the rate you see may not be the rate offered after lender assessment. - read more
|
Follow us!
Financial Services Online on social media
Stay up-to-date with the latest news, views, products, information & resources from Financial Services Online