Applying for a car loan with bad credit in Australia can feel uncertain, especially if you have missed repayments, defaults, debt arrangements or previous declined applications on your credit file. Some borrowers may still be able to apply for car finance, but approval is not automatic and the loan may cost more or come with tighter conditions.
This guide explains how bad credit car loans are commonly assessed, what lenders may be concerned about, how to prepare before applying and what risks to watch for. It is general information only and does not take your personal financial situation into account.
Can you apply for a car loan with bad credit?
Yes, someone with bad credit can generally apply for a car loan in Australia. Whether an application is approved depends on the lender’s criteria, your income, expenses, existing debts, credit history, the vehicle being financed and whether the loan appears affordable.
Bad credit does not always mean the same thing to every lender. One lender may view a past default differently from another, particularly if it has been paid, explained and followed by a period of stable repayments. However, a weaker credit history can affect:
- the lenders or loan products available to you;
- the interest rate and fees you may be offered;
- the deposit or security required;
- the maximum amount you may be able to borrow;
- the level of documentation requested; and
- whether a lender is comfortable approving the application at all.
If you are still comparing options, you can review general car finance options before deciding whether to submit an application.
What does “bad credit” usually mean?
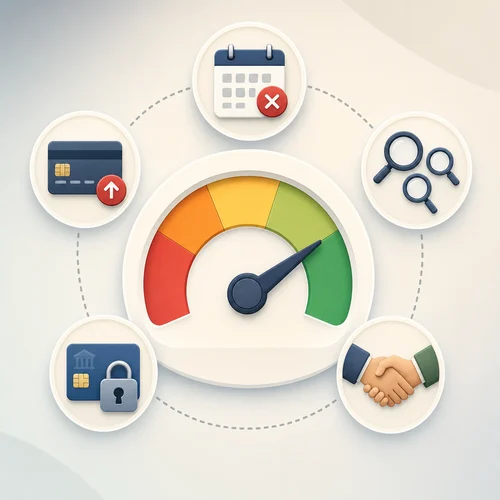
Bad credit is not a single official category. It is a broad way of describing a credit history that may make a lender see an application as higher risk. Examples can include:
- missed repayments on loans, credit cards or utilities;
- defaults or unpaid debts listed on a credit report;
- multiple recent credit applications;
- bankruptcy, debt agreements or insolvency events;
- accounts in hardship arrangements;
- limited credit history combined with unstable income; or
- a pattern of high credit card balances or overdrawn accounts.
Your credit score is only one part of the assessment. Lenders may also review the details behind the score, including the timing, amount and status of any negative listings. For more background, see how your credit score affects car finance options.
How lenders may assess bad credit car finance in Australia
When assessing a car loan with bad credit, lenders generally want to understand two things: the risk of lending to you and whether the proposed repayments are affordable. Their assessment may include the following factors.
Credit history and recent conduct
A lender may look at your credit report, repayment history and recent enquiries. A past issue may be viewed differently if it is old, resolved and supported by more recent evidence of on-time payments. Recent missed repayments can be more concerning because they may suggest current financial pressure.
Income stability
Lenders commonly check whether your income is regular, verifiable and sufficient to support the proposed repayments. PAYG employees, contractors, sole traders and business owners may be asked for different documents. Casual, seasonal or self-employed income may need extra explanation.
Expenses and existing debts
Your rent or mortgage, living expenses, credit cards, personal loans, buy now pay later commitments and other debts can all affect borrowing capacity. Even if your income is reasonable, high existing commitments may reduce the amount a lender considers affordable.
Deposit and loan-to-value risk
A deposit can reduce the amount borrowed and may lower the lender’s risk. It does not guarantee approval, but it can sometimes strengthen an application by showing savings discipline and reducing the loan compared with the vehicle value.
The vehicle being financed
For secured car loans, the vehicle often matters. Lenders may consider the age, condition, value, kilometres, seller type and whether the vehicle is acceptable as security. A lower-cost, reliable vehicle may be easier to assess than a vehicle that stretches your budget.
The explanation behind past credit problems
If your credit issues were linked to a specific event, such as job loss, illness, separation or business disruption, a lender may ask what changed and whether your finances have stabilised. Be honest and consistent. A clear explanation supported by documents is usually stronger than avoiding the issue.
Common options for borrowers with weaker credit
There is no single “bad credit car loan” that suits every borrower. Depending on your situation, options may include:
- Secured car finance: the vehicle is used as security, which may reduce some lender risk but can also mean the car may be at risk if repayments are not made.
- Specialist or flexible-credit lenders: some lenders consider applicants with past credit issues, although pricing and conditions may vary significantly.
- A smaller loan amount: choosing a less expensive vehicle or increasing your deposit may make the application easier to assess.
- Waiting before applying: delaying the application may give you time to reduce debts, correct credit report errors or build a stronger repayment record.
- Joint applications or guarantor arrangements: these may be available in some cases, but they create serious responsibilities for the other person and should be considered carefully.
Before relying on any option, ask how the loan works, what happens if you miss repayments and what total cost you will pay over the full term.
Costs and trade-offs to understand before applying
Borrowers with weaker credit histories may be offered different terms from borrowers with stronger credit profiles. The key is to compare the full cost and risk, not just whether a lender may consider the application.
| Loan feature | Why it matters with bad credit |
|---|---|
| Interest rate | A higher-risk application may attract a higher rate, which can increase total repayment cost. |
| Comparison rate | This can help show the combined effect of the interest rate and certain fees, although it may not include every cost. |
| Loan term | A longer term may reduce each repayment but can increase total interest paid over time. |
| Fees | Application, establishment, monthly, late payment or early payout fees can affect affordability. |
| Balloon payment | A balloon may reduce regular repayments but leaves a larger amount due at the end of the term. |
| Secured loan conditions | If the vehicle secures the loan, default can have serious consequences, including repossession processes. |
| Add-on products | Insurance, warranties or protection products may increase the amount financed and should be assessed separately. |
Check affordability before you apply
A car loan may be available but still be unsuitable for your budget. Before applying, estimate the repayment under different scenarios and include running costs such as registration, insurance, servicing, tyres, fuel or charging, tolls and repairs.
A loan calculator can help you test how the loan amount, term and interest rate assumptions may affect repayments. Treat the result as an estimate only. Actual repayments, fees and approval conditions depend on the lender, loan type and your circumstances.
It can also help to ask yourself:
- Could I still afford the loan if my hours were reduced or expenses increased?
- Have I allowed for insurance and maintenance, not just the loan repayment?
- Will the loan leave room for emergency savings?
- Am I choosing a vehicle because it is affordable, or because I am trying to meet a preferred monthly repayment?
Documents that may strengthen a bad credit car loan application
Being organised does not guarantee approval, but incomplete or inconsistent information can delay an assessment or weaken an application. Depending on the lender and applicant type, documents may include:
- proof of identity;
- recent payslips or employment details;
- bank statements;
- details of rent, mortgage and living expenses;
- statements for existing loans, credit cards or other debts;
- evidence that defaults or overdue accounts have been paid or are under arrangement;
- tax returns, BAS, financial statements or accountant information for self-employed applicants;
- vehicle details, such as sale contract, registration information or dealer invoice; and
- a written explanation for past credit issues, where relevant.
If you are unsure what documents may be needed, you can ask questions before applying. Speaking with a finance professional or broker may help you understand what information could be relevant, although broker or lender outcomes still depend on your circumstances and provider criteria.
How to reduce credit-file damage when shopping around
If you already have weaker credit, it is worth being careful about unnecessary applications. Multiple hard credit enquiries in a short period can make some lenders more cautious, especially if they suggest you are under pressure or applying widely without a clear plan.
Before submitting a formal application:
- check your credit report for errors or outdated information;
- compare eligibility criteria before applying;
- ask whether an initial assessment involves a soft or hard credit check;
- avoid applying for several loans at once without understanding the impact;
- make sure your income, expenses and debts are accurate; and
- only apply for an amount that fits your budget and the vehicle’s value.
Warning signs to watch for
Borrowers worried about their credit can be vulnerable to pressure or unclear offers. Take extra care if you encounter:
- pressure to sign immediately before reading the contract;
- a focus only on weekly or monthly repayments without explaining total cost;
- unclear fees, add-ons or balloon payments;
- reluctance to provide written loan details;
- claims that your credit history does not matter at all;
- suggestions to provide inaccurate information; or
- loan terms that rely on refinancing later to remain affordable.
Do not sign a loan contract unless you understand the repayment amount, frequency, total cost, fees, security, default consequences and whether optional products are included.
When it may be better to wait
Sometimes the most practical decision is to delay applying. Waiting may be worth considering if you have recent missed payments, unstable income, high debt, no emergency savings or uncertainty about whether the vehicle is affordable.
During that time, you may be able to:
- pay bills and existing credit accounts on time;
- reduce credit card balances or other debts;
- save a larger deposit;
- resolve overdue accounts;
- correct errors on your credit report;
- choose a lower-cost vehicle; or
- build a clearer record of stable income.
These steps may not remove past credit issues, but they can help present a clearer and more stable application later.
Questions to ask before applying for bad credit car finance
Before you submit an application, consider asking:
- What credit checks will be performed, and when?
- What documents are needed for my employment or business type?
- What interest rate, comparison rate and fees may apply?
- Is the loan secured against the vehicle?
- Are there early repayment, late payment or account-keeping fees?
- Is there a balloon payment or residual amount?
- Are any add-on products optional?
- What happens if I miss a repayment?
- Can I receive the key terms in writing before deciding?
Final Thoughts
Bad credit does not automatically prevent someone from applying for a car loan in Australia, but it can affect lender choice, pricing, documentation and approval prospects. The safest approach is to understand your credit position, test affordability, prepare accurate documents and compare the full loan cost before applying.
A car loan should fit your broader financial situation, not just solve an immediate transport need. If the repayments would leave you under pressure, it may be worth considering a cheaper vehicle, a larger deposit, a delayed purchase or independent financial counselling before taking on new debt.