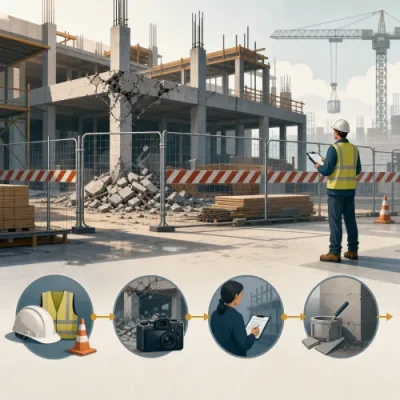
Damage, theft or loss on a construction site can interrupt work quickly. A contract works insurance claim is generally designed to help deal with insured damage to the works, materials or other covered property during a project, subject to the policy terms, exclusions, excesses and insurer assessment.
This guide explains the general contract works claim process for Australian builders, contractors and site managers. It is not personal advice, and actual claim handling will depend on your policy wording, the cause of loss, the evidence available and the insurer's requirements. If you are still reviewing cover options, you can start with general information about Contract Works Insurance.
Start with safety, site control and incident response
The first priority after construction site damage is not the insurance paperwork. It is making the site safe and preventing further harm.
Depending on the incident, this may involve:
- checking whether anyone is injured and arranging emergency assistance if needed;
- isolating unsafe areas, temporary services or damaged structures;
- securing the site after theft, vandalism, storm damage or fire;
- notifying police for theft, malicious damage or suspected criminal activity;
- protecting undamaged materials, plant or partially completed works from further damage;
- recording what temporary steps were taken and why.
Policy conditions often require insured parties to take reasonable steps to minimise further loss. However, major repairs, demolition or disposal of damaged items should generally not proceed before the insurer has had a chance to inspect, unless urgent safety or loss mitigation makes this unavoidable.
Step 1: Check the policy and notify the right parties
Once the immediate risk is under control, the next step is to review the relevant contract works insurance policy and notify the insurer, broker or authorised claims contact as soon as reasonably practicable.
The policy wording can help confirm:
- which project, site or annual turnover arrangement is insured;
- who is listed as insured or covered under the policy;
- whether the incident occurred during the insured period;
- what property or works are insured;
- the excess that may apply;
- any special conditions relating to site security, hot works, flood, storm, theft, temporary works or subcontractors;
- whether separate sections, such as public liability or plant cover, may also be relevant.
A construction site damage claim may involve more than one party. The builder, principal, project owner, subcontractors, superintendent or financier may have contractual notification obligations. Those obligations are separate from the insurance claim itself, so it is worth checking the building contract as well as the insurance policy.
Step 2: Preserve evidence before the site changes
Construction sites change quickly. Evidence that is obvious on the day of the incident may be gone by the time an assessor or loss adjuster attends. Clear records can make the claim easier to understand and assess.
Useful evidence may include:
- photos and videos of the damaged works, surrounding area and point of entry if theft is involved;
- the date and time the loss was discovered;
- site diary entries and daily reports;
- weather information if storm, rain or flood is relevant;
- police event numbers or reports for theft, vandalism or burglary;
- witness names and contact details;
- invoices, delivery dockets and purchase orders for stolen or damaged materials;
- contracts, plans, variations and scopes of work;
- quotes for repair, reinstatement or replacement;
- records of temporary works or emergency make-safe expenses.
For a site theft insurance claim, insurers will usually want a clear inventory of what was stolen, when it was last seen, who had access to the site and what security measures were in place. Evidence of ownership and value is often important.
Step 3: Lodge the claim with enough detail
The claim lodgement process will vary between insurers and brokers, but the core information is usually similar. The aim is to give the insurer enough detail to identify the policy, understand what happened and decide what further assessment is required.
| Information commonly requested | Why it matters |
|---|---|
| Policy number, insured name and project address | Helps identify the correct policy and insured project. |
| Date and time of loss or discovery | Helps determine whether the incident falls within the insured period. |
| Description of the incident | Helps the insurer assess the likely cause and applicable policy section. |
| Photos, videos and site records | Supports the extent and nature of the damage or loss. |
| Police report details for theft or vandalism | Supports criminal loss claims and may be required by the policy. |
| Estimated cost of repair or replacement | Helps the insurer reserve the claim and decide whether an assessor is needed. |
| Details of urgent make-safe work | Shows what was done to reduce further loss or safety risk. |
It is better to be accurate than to guess. If some information is not yet available, it can often be provided later. Builders insurance claims can become more difficult where early estimates are treated as final numbers or where key records are not retained.
Step 4: The insurer may appoint an assessor or loss adjuster
For larger or more complex claims, the insurer may appoint a loss adjuster, assessor, engineer, quantity surveyor or other specialist. Their role is to investigate the circumstances, inspect the damage and provide information to the insurer.
The assessment may consider:
- the cause of the damage or loss;
- whether the damaged property is insured under the policy;
- whether the incident falls within the policy period and project scope;
- whether exclusions, limits, sub-limits or conditions apply;
- whether the claimed costs are reasonable and supported;
- whether any other party may be responsible for the loss;
- whether temporary repairs, staged repairs or full reinstatement are appropriate.
An assessor's involvement does not automatically mean a claim will be accepted or declined. It is part of the fact-finding process. The insurer will usually make the coverage decision based on the policy terms, evidence and assessment findings.
Step 5: Coverage, excesses and exclusions are considered
A contract works insurance policy does not cover every problem that can occur on a building site. The insurer will consider whether the event is covered and whether any exclusions or conditions affect the outcome.
Common areas that may need close review include:
- Defective workmanship or design: Policies may treat the cost of correcting defects differently from damage caused by an insured event. The distinction can be important.
- Gradual damage: Wear, deterioration, corrosion or gradual water ingress may be handled differently from sudden and accidental damage.
- Theft conditions: A policy may contain requirements about forcible entry, locked storage, fencing, lighting or security procedures.
- Weather events: Storm, flood, water damage and inadequate protection of works may be subject to specific definitions or exclusions.
- Existing structures: Renovation and extension projects may need special attention because existing structures are not always covered in the same way as new works.
- Subcontractor property: Materials, tools, plant or temporary works belonging to subcontractors may not automatically be covered unless the policy says so.
- Underinsurance or incorrect project values: If the declared value or insured amount does not reflect the project properly, the claim outcome may be affected depending on the policy.
The applicable excess will also be considered. Different excesses may apply depending on the type of claim, location, cause of loss or policy section.
Step 6: Repair, reinstatement and settlement are agreed
If the claim is accepted, the insurer will usually work through the appropriate repair or reinstatement approach. This may involve approving a scope of works, reviewing quotes, agreeing replacement materials or paying approved costs under the policy.
Settlement may occur in different ways depending on the policy and circumstances. For example, the insurer may approve repair invoices, reimburse supported costs, make staged payments or settle an agreed amount. The process can be affected by project urgency, availability of materials, specialist trades, safety requirements and whether the works need to continue while repairs are underway.
Builders and site managers should keep clear records of approved repairs and costs. If additional damage is discovered after work starts, notify the insurer or broker before assuming the extra cost is covered.
Common issues that can slow down a contract works claim
Some claim delays are unavoidable, especially where damage is complex or specialist reports are needed. Others can be reduced with better preparation.
Common issues include:
- late notification to the insurer;
- repairs completed before the damage is documented or assessed;
- missing invoices or proof of ownership for stolen materials;
- unclear responsibility between the builder, principal and subcontractors;
- uncertainty about whether the damaged item was part of the insured works;
- project variations that were not reflected in the insured value;
- lack of site security records after a theft or vandalism claim;
- confusion between contract works cover and public liability cover.
Contract works insurance generally relates to damage to insured works or property. Public liability cover is usually concerned with third-party injury or property damage. If an incident involves both damage to the works and damage to someone else's property, more than one policy section or policy may need to be considered.
What to prepare before an incident happens
The easiest time to improve claim readiness is before a loss occurs. A simple claims file for each project can save time later.
Consider keeping:
- a copy of the contract works policy schedule and wording;
- the insurer or broker claims contact details;
- the construction contract and project scope;
- approved plans, specifications and variations;
- site security procedures and access records;
- delivery dockets and invoices for major materials;
- photos of progress at key stages;
- subcontractor agreements and insurance details where relevant;
- a process for reporting incidents quickly.
If you are unsure how your policy should respond to a particular incident, a broker may be able to help interpret the policy wording and guide the claims notification process. You can find general broker information through the site's Brokers page.
Key takeaway
A contract works insurance claim is usually handled through a sequence of notification, evidence gathering, assessment, coverage review and settlement or repair approval. The smoother claims are often those where the site is made safe, the insurer is notified promptly, evidence is preserved and costs are clearly documented.
Every policy is different. Before relying on cover, check the wording, exclusions, excesses, insured values and project-specific conditions. If damage or theft has already occurred, act quickly, keep records and avoid assuming the outcome until the insurer has assessed the claim.