Understanding boat loans in Australia
A boat loan is a finance agreement where a lender provides funds for a vessel purchase and the borrower repays the amount, plus interest, over an agreed period. Loan conditions can vary widely, including the interest rate, repayment term, documentation requirements and whether an asset is used as security.
In Australia, boat finance may be offered by major banks, credit unions and specialised marine finance providers. Some borrowers also use brokers or finance intermediaries to understand available products and lender requirements. The right structure depends on the borrower's circumstances, the vessel being purchased and the loan terms offered.
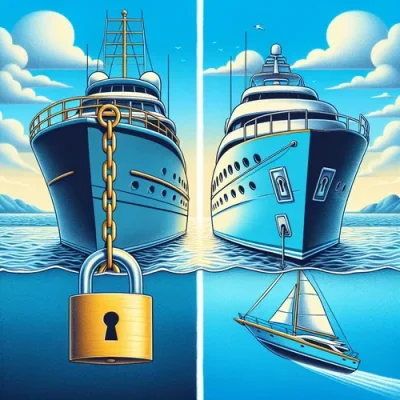
The two broad loan types commonly compared are secured boat loans and unsecured boat loans. Neither is automatically better for every borrower. Each involves trade-offs between cost, flexibility, collateral and risk.
What is a secured boat loan?
A secured boat loan is a loan supported by collateral. In many cases, the boat being purchased is used as the security for the loan. If the borrower defaults and the lender's recovery process applies, the lender may be able to repossess and sell the secured asset to help recover the outstanding debt.
Because the lender has an asset to rely on if repayments are not made, secured loans are often viewed as lower risk for lenders than unsecured loans. This can mean secured boat loans may offer lower interest rates or longer loan terms than comparable unsecured options, although actual terms depend on the lender, borrower profile and asset details.
Potential advantages of secured boat loans
- They may have lower interest rates than unsecured boat loans because the lender has collateral.
- They may allow longer repayment terms, which can reduce the regular repayment amount.
- They may suit higher-value boat purchases where unsecured borrowing limits are not sufficient or are less competitive.
- They can be appropriate where the borrower is comfortable using the vessel, or another acceptable asset, as security.
Risks and limitations of secured boat loans
- The secured asset may be at risk if repayments are not made.
- The lender may require details about the boat, such as make, model and valuation.
- The loan may have conditions about the vessel, including age, type or acceptable value.
- A longer term may lower regular repayments but can increase the total interest paid over time.
A secured loan may be worth considering for borrowers who want to minimise interest costs, can manage consistent repayments and are comfortable with the collateral implications. It may also be relevant when buying a higher-value vessel where the loan amount and term are important factors.
What is an unsecured boat loan?
An unsecured boat loan does not require the borrower to pledge the boat or another asset as security. Instead, the lender assesses the borrower's creditworthiness, income, financial stability and ability to repay.
Because there is no collateral attached to the loan, unsecured finance generally exposes the lender to more risk. As a result, unsecured boat loans typically have higher interest rates than secured loans and may have shorter terms or lower maximum loan amounts.
Potential advantages of unsecured boat loans
- No boat or other asset is pledged as security for the loan.
- The application process may be simpler or faster because there is no asset valuation process for collateral.
- There may be fewer restrictions on the boat's age or type compared with some secured loans.
- They can suit lower-cost purchases where secured finance savings may be less significant.
Risks and limitations of unsecured boat loans
- Interest rates are typically higher than secured options because the lender has no collateral.
- Loan terms may be shorter, which can increase regular repayments.
- Borrowing limits may be lower, which can restrict the type of boat that can be financed.
- If the borrower defaults, the lender may still take recovery action, and missed payments can affect credit history and future borrowing capacity.
An unsecured loan may suit borrowers who do not want to use an asset as security and who have the income and credit profile to meet lender requirements. It may also suit buyers of lower-priced boats or borrowers who want to avoid tying the vessel to the loan.
Secured vs unsecured boat loans: key differences
The main difference is collateral, but that difference affects several parts of the loan. The table below summarises the common trade-offs.
| Feature | Secured boat loan | Unsecured boat loan |
|---|---|---|
| Collateral | Usually secured against the boat or another acceptable asset. | No asset is pledged as security. |
| Interest rates | Often lower because the lender has security. | Often higher because the lender takes on more risk. |
| Loan term | May allow longer terms, depending on the lender and asset. | May have shorter terms. |
| Regular repayments | Can be lower if the rate is lower or the term is longer. | Can be higher if the rate is higher or the term is shorter. |
| Borrowing amount | May be more suitable for higher-value purchases. | May be limited to smaller loan amounts. |
| Asset risk | The secured asset may be repossessed if the loan defaults. | No secured asset is attached, but default can still lead to recovery action and credit impacts. |
| Boat requirements | The lender may assess the boat's make, model, condition and value. | May involve fewer vessel-specific restrictions. |
Interest rates and total loan cost
Secured boat loans typically have lower interest rates because the lender has an asset as security. Unsecured loans usually have higher interest rates to reflect the greater risk to the lender.
Interest rate is important, but it is not the only cost factor. Loan term, fees, repayment frequency and whether the loan is repaid early can all affect the total amount paid. A longer secured loan term may reduce regular repayments, but it can also result in paying interest for a longer period.
Before choosing a loan type, it can help to estimate repayments under different rates and terms. A boat loan repayment calculator can be used to model how the loan amount, interest rate and term may affect repayments.
Collateral, default risk and credit impacts
Collateral is the defining feature of a secured boat loan. If the borrower does not meet repayment obligations, the lender may be able to take action in relation to the secured asset. This is why borrowers should understand exactly what asset is being used as security and what the loan agreement allows the lender to do if default occurs.
With an unsecured loan, there is no specific asset pledged as security. However, that does not mean missed repayments have no consequences. A lender may still pursue recovery processes, and repayment problems may affect the borrower's credit history and future ability to borrow.
In both cases, borrowers should read the loan agreement carefully and consider how they would manage repayments if income or expenses changed unexpectedly.
How to decide which boat loan type may suit your circumstances
The choice between secured and unsecured boat finance should be based on the borrower's financial position, risk tolerance, vessel details and loan offers available at the time. Useful factors to compare include the following.
Your budget and ongoing ownership costs
A boat buying budget should include more than the purchase price. Ongoing costs can include maintenance, insurance, fuel, storage and other ownership expenses. These costs can affect how much room is available for loan repayments.
For a broader look at vessel-related budgeting, see this guide to budgeting beyond the boat purchase price.
Your preference on collateral
If avoiding secured asset risk is a priority, an unsecured loan may be more appealing, even if the rate is higher. If minimising interest costs is a priority and the borrower is comfortable offering collateral, a secured loan may be more suitable to compare.
Your credit history and income stability
Credit history and income stability can influence whether a lender approves an application and what terms are offered. A stronger credit profile may support access to more favourable terms, while a weaker profile may limit options or increase the cost of borrowing.
The value and type of boat
Higher-value boats may be more commonly financed through secured loans because the vessel can support the loan as collateral. Lower-cost purchases may sometimes be handled through unsecured finance, depending on borrowing limits and the borrower's profile.
How long you expect to own the boat
Borrowers planning to keep a boat for a longer period may place more weight on interest rate and total cost. Borrowers expecting a shorter ownership period may pay closer attention to loan flexibility, term length and exit conditions.
Applying for a boat loan in Australia
Whether the loan is secured or unsecured, a well-prepared application helps the lender assess the request. The process generally involves identifying the type of loan required, comparing lenders, gathering documents and reviewing the proposed loan agreement before signing.
If you are ready to research current options, you can compare boat loan options as part of your broader finance review.
Common application steps
- Decide whether you want to compare secured, unsecured or both types of boat finance.
- Review your budget, income, expenses, debts and savings.
- Check your credit history so you understand what lenders may see.
- Research lenders, including banks, credit unions and specialised marine finance providers.
- Gather documents such as identification, proof of income and financial statements.
- Provide boat details where required, particularly for secured finance.
- Submit the application and respond to any lender requests for more information.
- Review the loan agreement, including the rate, term, fees, repayment schedule and security conditions, before signing.
For more detail on the typical steps, read this guide to how the boat loan application process works in Australia.
Documents lenders may request
- Identification, such as a driver licence or passport.
- Proof of income, such as recent pay slips or tax returns.
- Bank statements and information about assets and liabilities.
- Details of existing loans, credit cards and other debts.
- For secured loans, boat details such as make, model and valuation information.
Some borrowers may also choose to speak with a broker or finance professional to understand lender requirements and product differences. You can learn more about the role of boat finance brokers if you are considering professional assistance.
Questions to ask before choosing
- What is the interest rate, and is it fixed or variable?
- What fees apply during setup, repayment or early payout?
- What is the loan term, and how does it affect total interest?
- Is the boat or another asset being used as security?
- What happens if repayments are missed?
- Are there restrictions on the boat's age, type, condition or value?
- Can extra repayments be made, and are there limits or fees?
- How do the regular repayments fit with ongoing boating costs?
Bottom line
Secured boat loans and unsecured boat loans both have a place in the Australian marine finance market. A secured loan may offer lower rates or longer terms, but it requires collateral and carries asset risk. An unsecured loan avoids pledged collateral, but it usually costs more and may have shorter terms or lower borrowing limits.
The most appropriate option depends on the borrower's budget, credit profile, income stability, preferred risk level, boat value and the loan terms available. Comparing the full cost and understanding the repayment obligations is essential before entering any finance agreement.
Published: Friday 6th September, 2024
Last updated: Wednesday 19th August, 2026