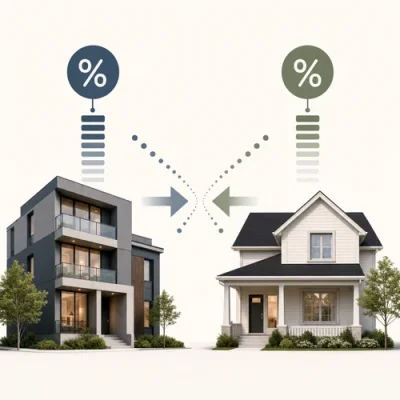

The latest narrowing does not mean investor loans are suddenly interchangeable with owner-occupier loans. Loan purpose, repayment type, deposit size, security, income profile and credit history still influence pricing. However, it does suggest borrowers may need to look beyond the old assumption that investor finance will always carry a large rate penalty.
For property investors, the change may improve the case for reviewing existing loans. A small rate difference can affect cash flow, especially when combined with strata fees, land tax, maintenance, insurance and periods without rental income. It may also influence whether borrowers choose principal-and-interest repayments or interest-only terms, although lower short-term repayments can increase long-term interest costs.
Owner-occupiers should also pay attention. When lenders compete harder for investor loans, they may adjust discounts, cashback offers, package fees or loan features across the broader mortgage market. This can make headline rates less useful as a comparison tool. The better question is how the full loan structure works over time, including fees, offset account value, redraw access, repayment flexibility and refinancing costs.
For households considering a switch, it is worth using current loan details to model repayments under several scenarios. A lower rate may not deliver a better outcome if the new loan extends the term too far, adds fees or removes features that reduce interest in practice.
The development also matters for first-time investors who are weighing property against other options. A narrower rate gap can make investment borrowing appear more attractive, but it does not remove market risk. Rental income can change, property values can fall, and tax outcomes depend on personal circumstances. Borrowers should avoid stretching capacity simply because pricing looks more competitive.
The practical takeaway is that mortgage categories are becoming less useful as a shortcut for value. Whether borrowing to invest or to live in the property, Australians should compare loan options using total cost, suitability and resilience under higher-rate or lower-income conditions, not just the advertised rate.
Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.