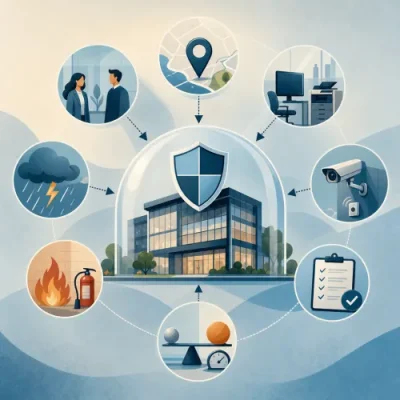
Office insurance cost in Australia is not based on a single fixed price. Two businesses in similar-looking offices may receive different premiums because insurers assess what the business does, what assets are insured, where the office is located, the level of cover requested and the likelihood or potential size of a claim.
This article explains the main office insurance quote factors Australian business owners may encounter when comparing policies. It is general information only and does not consider your business objectives, financial situation or needs. Premiums, excesses, eligibility and cover availability depend on the insurer, policy wording and your individual circumstances.
Why office insurance premiums vary
Office insurance is usually priced according to risk. An insurer will generally consider how likely it is that a claim may occur and how expensive that claim could be. The more complex the business, the higher the value of insured property, or the greater the potential liability exposure, the more detailed the pricing assessment may be.
For example, a small consulting office with limited visitors and modest equipment may present a different risk profile from a larger office that stores expensive technology, receives regular clients, handles sensitive customer information and depends on uninterrupted access to its premises.
If you are at the early research stage, the Office Insurance Solutions homepage provides a quote pathway for businesses comparing office insurance options. Before requesting quotes, it can help to understand the factors insurers may ask about.
Business activities and industry risk
One of the most important pricing factors is what your business actually does. Insurers are not only assessing the physical office; they are also assessing the work performed from that office and the types of claims that could arise.
Activities that may influence business insurance premiums include:
- Professional services provided: Advice-based, consulting, design, technology, finance, legal, marketing or other professional work may create different liability exposures.
- Client interaction: Offices with frequent visitors, meetings, workshops or events may have different public liability considerations from offices with little public access.
- Handling of third-party property: If the business stores client equipment, documents or stock, this may affect the type and amount of cover required.
- Data and cyber exposure: Businesses that collect, store or process sensitive information may need to consider cyber-related risks and optional cyber cover.
- Work performed away from the office: If employees regularly visit client sites, attend events or work remotely, the insurer may need to understand where and how the business operates.
A business description that is too vague can make quote comparisons difficult. When requesting office insurance quotes, describe the main revenue-generating activities, any higher-risk services, and whether the office is used mainly for administration, client-facing work, storage or operations.
Office location and premises characteristics
Location can affect commercial office insurance cost because different premises may face different risks. Insurers may consider the building type, occupancy, surrounding businesses, local exposure to storm or flood, crime risk, fire protection and access arrangements.
Factors connected to the premises may include:
- whether the office is in a commercial building, shared workspace, retail strip, industrial estate or home-based office setup;
- whether the business owns or leases the premises;
- building security, including locks, alarms, monitored systems and access control;
- fire safety features and building maintenance standards;
- whether the office is on the ground floor or in a multi-storey building;
- proximity to other occupancies that may increase or reduce risk;
- the presence of storage areas, server rooms, kitchens or specialist equipment rooms.
Leasing arrangements can also matter. A landlord may insure the building, while the tenant may need to insure office contents, fit-out, glass, liability, business interruption or other business-specific risks. The exact split depends on the lease and policy wording.
Value of office contents, equipment and fit-out
The amount of property you want to insure is a key premium driver. Higher insured values can increase the potential cost of a claim, which may increase the premium.
Office property may include:
- computers, laptops, monitors and peripherals;
- phones, printers, scanners and communications equipment;
- furniture, desks, chairs and cabinetry;
- specialist equipment used in your business;
- leased equipment that you are responsible for insuring;
- office stock, samples or promotional material;
- tenant improvements, fixtures, signage or fit-out.
Underinsuring property can create problems at claim time, while overestimating values may increase premiums unnecessarily. Businesses should consider replacement costs rather than only the depreciated value of older equipment, unless the policy wording uses a different settlement basis.
Revenue, staff numbers and business size
Insurers often ask about annual turnover, payroll, number of employees, contractors and business locations. These details help insurers understand the scale of the operation and potential exposure.
A business with higher revenue may have more clients, larger contracts or greater potential financial consequences if something goes wrong. More staff may also mean more equipment, more visitors, more travel and a greater operational footprint.
Common business size indicators include:
- annual turnover or projected turnover;
- number of full-time, part-time and casual employees;
- use of contractors, freelancers or labour hire;
- number of office locations;
- whether the business operates interstate or internationally;
- the value of contracts or client work performed.
Startups and growing businesses should review these details regularly. A policy arranged when the business was small may no longer reflect the current risk profile if revenue, staff numbers or services have changed.
Types of cover included in the policy
Office insurance is often a package of different cover types rather than one single cover. The cost will depend on what sections are selected, the limits chosen and the exclusions that apply.
| Cover type | How it may affect cost |
|---|---|
| Property or contents cover | Premiums may increase with higher insured values, specialist equipment or broader events covered. |
| Public liability insurance for office visitors | Pricing may depend on visitor numbers, premises use, business activities and requested liability limits. |
| Professional indemnity | Cost may depend on the services provided, contract values, professional qualifications, claims history and limit selected. |
| Business interruption | Pricing may reflect turnover, dependency on premises, indemnity period and the time needed to resume operations. |
| Theft, money or portable property | Premiums may depend on security, property values, whether equipment is taken off-site and any sub-limits. |
| Cyber cover | Pricing may consider data handling, digital systems, security practices and the cover limit requested. |
Not every office needs every available section, and some covers may be essential for one business but unnecessary for another. The relevant mix depends on your operations, contracts, premises and risk tolerance.
Policy limits, sub-limits and excesses
Policy limits are the maximum amounts an insurer may pay for a covered claim, subject to policy terms, conditions and exclusions. Choosing higher limits can increase premiums because the insurer is taking on a larger potential exposure.
Sub-limits can also affect cover. A policy may have an overall limit but lower limits for certain items or events, such as portable equipment, temporary removal of contents, money, glass, data restoration or additional increased costs of working.
The office insurance excess is another important cost factor. An excess is the amount you contribute towards a claim before the insurer pays the balance, where the claim is accepted. In some cases, choosing a higher excess may reduce the premium, but it also means the business carries more upfront claim cost. A lower excess may make smaller claims easier to manage, but premiums may be higher.
When comparing office insurance policies, consider both the premium and the excess. A cheaper premium is not necessarily better if the excess, exclusions or sub-limits make the cover unsuitable for the risks you want to insure.
Claims history and risk management
Previous claims can influence small business insurance pricing. Insurers may ask about past losses, declined claims, cancelled policies or circumstances that could lead to a claim. A history of frequent or severe claims may affect premiums, excesses, conditions or availability of cover.
Risk management may also be considered. Measures that reduce the likelihood or severity of claims can help present the business more clearly to insurers, although they do not guarantee lower premiums or acceptance.
Examples of risk management measures include:
- documented workplace safety procedures;
- secure storage for equipment and records;
- regular electrical testing or equipment maintenance where relevant;
- cybersecurity practices such as backups, access controls and staff training;
- visitor management and clear walkways;
- fire safety checks and evacuation procedures;
- contract review processes for professional services businesses.
For a deeper look at this topic, see The Role of Risk Management in Minimising Office Insurance Expenses. Risk controls are most useful when they are practical, documented and maintained over time.
Business interruption needs
Business interruption cover can be an important part of office insurance for businesses that would lose income or incur extra costs if the premises could not be used after an insured event. The cost may depend on the turnover insured, the indemnity period, payroll treatment and how quickly the business could reasonably resume operations.
Insurers may consider questions such as:
- Could staff work remotely if the office was damaged?
- How long would it take to replace equipment or rebuild systems?
- Would clients wait, or would revenue be lost quickly?
- Are there specialist premises, licences or equipment that would be hard to replace?
- Would temporary premises or additional technology be required?
A business with strong remote-work capability may have a different interruption profile from one that relies on a fixed premises, on-site servers or physical client access. However, every policy is different, so the wording should be checked carefully.
Optional extensions and additional benefits
Optional extensions can broaden cover but may add to the premium. These options can be useful where they match a genuine risk, but they should be considered carefully rather than added automatically.
Common optional or additional cover areas may include:
- portable equipment used away from the office;
- glass cover for leased premises;
- tax audit cover;
- management liability;
- employment practices liability;
- cyber incidents and data recovery;
- machinery or electronic equipment breakdown;
- transit cover for business property;
- increased costs of working after an insured event.
Some extensions may be included automatically, some may be subject to sub-limits and some may be unavailable depending on the insurer or business type. Always check whether an extension is included, optional, excluded or subject to special conditions.
Security, maintenance and office procedures
Practical security and maintenance measures may affect how insurers view the risk. They can also reduce the chance of disruption, theft, injury or property damage.
Relevant measures may include:
- deadlocks, monitored alarms or access control;
- secure storage for laptops and portable devices;
- regular backups stored securely;
- maintenance of air conditioning, electrical systems and water fittings;
- clear incident reporting procedures;
- staff training for cybersecurity, emergency response and visitor safety;
- clear records of assets, serial numbers and purchase documents.
These measures do not guarantee cheaper insurance, but they may help when providing risk information to insurers and can improve claim preparedness.
How insurers may use quote information
When you request office insurance quotes, insurers or brokers may ask for information to assess eligibility, pricing and policy terms. The details requested will vary, but may include:
- business name, ABN and trading structure;
- industry and business activities;
- annual turnover and staff numbers;
- office address and premises details;
- value of contents, stock, equipment and fit-out;
- current insurance details and claims history;
- requested cover types, limits and excesses;
- security systems and risk management practices;
- whether the business operates online, interstate or overseas.
Providing accurate information matters. Incorrect or incomplete details may affect the quote, policy terms or claim outcome. If something changes after a policy starts, such as a new office location, extra services or a significant increase in equipment values, ask the insurer or broker whether the policy needs updating.
Using calculators and comparisons carefully
Online tools can help you think through cost inputs such as asset values, business size and cover needs. The site's calculators may be useful when preparing information before comparing office insurance quotes.
However, calculators and comparison tools are only guides. They cannot confirm the final premium, excess, cover availability or policy suitability. Final outcomes depend on insurer underwriting, policy wording and the information provided by the business.
How to compare office insurance cost more effectively
When comparing quotes, it can be tempting to focus only on the premium. A more useful comparison looks at the total value, limitations and responsibilities under each policy.
Consider comparing:
- Cover sections: Are the same types of cover included in each quote?
- Limits and sub-limits: Are the maximum claim amounts comparable?
- Excesses: How much would the business need to pay if a claim is made?
- Exclusions: What is not covered, and are any exclusions significant for your business?
- Conditions: Are there security, maintenance, reporting or contractual requirements?
- Business interruption terms: Is the indemnity period realistic for your recovery timeframe?
- Optional extensions: Are they included, excluded or available at extra cost?
- Claims process: What documentation and notification steps may be required?
A lower premium may reflect narrower cover, lower limits, higher excesses or exclusions that are important to your business. A higher premium may reflect broader cover, higher limits or risk factors that the insurer has priced into the policy.
Questions to ask before choosing a policy
Before selecting office insurance, it may help to ask:
- What business activities has the quote been based on?
- Are all office assets, portable equipment and fit-out values included?
- What events are covered for property damage, theft and interruption?
- What liability covers are included, and what limits apply?
- What excess applies to each type of claim?
- Are any exclusions particularly relevant to the business?
- Does the policy cover work performed away from the office?
- Does the business need cyber, professional indemnity or management liability cover separately?
- What information must be updated if the business changes?
If the policy wording is difficult to interpret, consider asking the insurer or a licensed insurance professional to explain how the policy responds to the risks you are concerned about.
Key takeaways on office insurance cost in Australia
Office insurance cost in Australia is influenced by a combination of business activities, location, property values, revenue, staff numbers, claims history, cover types, limits, excesses, optional extensions and risk management practices.
The aim is not simply to find the lowest upfront premium. A practical office insurance comparison looks at whether the policy reflects the risks of the business, the value of the assets insured, the potential consequences of interruption and the claim costs the business could absorb through excesses or exclusions.
Because insurers assess risks differently, quotes can vary. Preparing accurate information and comparing policies on a like-for-like basis can help Australian business owners make a more informed decision.