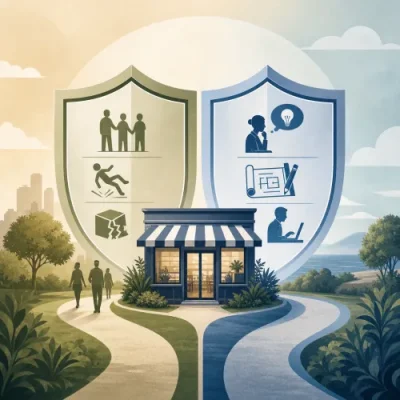
Public liability insurance and professional indemnity insurance are two common forms of business liability insurance in Australia, but they are designed for different risks. Public liability generally relates to injury or property damage suffered by third parties because of your business activities. Professional indemnity generally relates to financial loss suffered by a client because of your professional advice, services or work.
Understanding the difference matters because a business can be exposed to one risk, the other, or both. A trade business, consultant, allied health provider, designer, IT contractor or home-based professional may all face different liability exposures depending on what they do, where they work and what they promise to clients.
This article provides general information only. It does not consider your business objectives, financial situation or needs. Policy availability, pricing, limits, exclusions and claims outcomes depend on your circumstances and the insurer's criteria, so read the relevant policy documents and consider professional guidance where needed.
The short answer: what is the main difference?
The simplest way to separate the two covers is to ask what type of harm the claim is about.
- Public liability insurance is generally aimed at claims that a third party was injured or had their property damaged because of your business activities.
- Professional indemnity insurance is generally aimed at claims that a client suffered financial loss because of your professional advice, design, recommendation, service or omission.
For example, if a customer trips over equipment at your premises and is injured, that is typically the kind of scenario associated with public liability insurance. If a client alleges your professional advice caused them to lose money, that is typically the kind of scenario associated with professional indemnity insurance.
Public liability vs professional indemnity at a glance
| Feature | Public liability insurance | Professional indemnity insurance |
|---|---|---|
| Main risk covered | Third-party injury or third-party property damage linked to business activities | Client financial loss linked to professional advice, services, errors or omissions |
| Common claim example | A visitor slips at your workplace, or you damage a client's property while working on site | A client alleges your advice, design, report or professional service caused a financial loss |
| Commonly relevant for | Retailers, trades, market stallholders, hospitality businesses, mobile services and businesses that interact with the public | Consultants, advisers, designers, IT professionals, accountants, bookkeepers, engineers, health professionals and other service providers |
| Often requested by | Landlords, event organisers, councils, principal contractors and commercial clients | Professional bodies, regulators, government panels, larger clients and contract counterparties |
| Typical focus of cover | Compensation claims and legal defence costs for covered third-party injury or property damage claims | Compensation claims and legal defence costs for covered professional negligence, error or omission claims |
What public liability insurance may cover
Public liability insurance is designed to respond to covered claims by third parties, such as customers, suppliers, visitors or members of the public. It is commonly considered by businesses that have physical premises, visit client sites, work in public places, host events, sell goods in person or interact with customers face to face.
Depending on the policy, public liability insurance may help with covered claims involving:
- injury to a customer, visitor or member of the public connected to your business activities;
- damage to someone else's property caused by your business operations;
- legal defence costs associated with a covered claim;
- settlements or compensation amounts covered by the policy.
Public liability cover is not the same as workers compensation, which is a separate area involving employees and workplace injuries. It also does not automatically cover every business dispute, product issue, professional mistake or contractual penalty. The policy wording, exclusions and endorsements are important.
When an Australian business might need public liability insurance
An Australian business may consider public liability insurance where third parties could be injured or have property damaged because of its operations. It may also be required under a lease, licence, event agreement, client contract or contractor arrangement.
Public liability may be particularly relevant if your business:
- has customers, clients, couriers or suppliers visiting your premises;
- works at customer homes, offices, building sites or other third-party locations;
- operates at markets, festivals, trade shows or public events;
- uses tools, equipment, stock or displays in areas accessed by others;
- handles or works around other people's property;
- needs to satisfy contract, landlord or council insurance requirements.
For example, a plumber, electrician, cleaner, mobile hairdresser, café, retail store, market stallholder or fitness business may have public liability exposures because their work involves public interaction, property access or physical premises.
What professional indemnity insurance may cover
Professional indemnity insurance is designed for businesses that provide professional advice, specialist services, reports, designs, recommendations or expertise. It may help with covered claims where a client alleges that your professional work caused them a financial loss.
Depending on the policy, professional indemnity insurance may respond to covered allegations involving:
- professional negligence;
- errors, mistakes or omissions in advice or services;
- misleading or incorrect professional recommendations;
- breach of professional duty;
- certain confidentiality or intellectual property-related claims, if included;
- legal defence costs associated with a covered claim.
Professional indemnity policies are often written on a claims-made basis. This generally means the policy that responds may be the one in force when a claim is made or when you notify a relevant circumstance, rather than when the work was originally performed. Retroactive dates, continuity of cover and run-off cover can therefore be important, particularly if your business changes insurers, closes, merges or sells.
When an Australian business might need professional indemnity insurance
Professional indemnity insurance may be relevant if clients rely on your expertise to make decisions, manage risk, operate systems, meet obligations or spend money. It may also be required by professional associations, licensing arrangements, government panels, tenders or client contracts.
Professional indemnity may be particularly relevant if your business:
- gives advice, recommendations or professional opinions;
- prepares designs, plans, specifications, reports or documentation;
- manages projects, systems, data, compliance or financial processes for clients;
- provides consulting, coaching, technical or specialist services;
- works in a profession where insurance is required or commonly expected;
- could cause a client financial loss even without injuring anyone or damaging property.
Examples may include management consultants, IT consultants, marketing strategists, accountants, bookkeepers, engineers, architects, migration agents, training providers and some health or allied health professionals. The exact need depends on the work performed and the relevant contractual or professional requirements.
Can a business need both types of cover?
Yes. Many Australian small businesses need to consider both public liability and professional indemnity because they face both physical and professional risks. The covers are complementary rather than interchangeable.
For example, a web designer may meet clients at their studio or attend client offices, creating possible public liability exposure. The same web designer may also provide technical recommendations, project specifications or implementation work that could create professional indemnity exposure if a client alleges the work caused financial loss.
Similarly, an engineer may visit construction sites, creating potential public liability exposure, while also preparing reports or designs that clients rely on, creating potential professional indemnity exposure.
Examples by business type
| Business type | Public liability exposure | Professional indemnity exposure |
|---|---|---|
| Electrician or plumber | Damage to a client's property or injury to a third party while working on site | May arise if providing specialist design, certification or advice beyond standard trade work |
| Business consultant | Client or visitor injury at meetings, events or premises | Client alleges advice or recommendations caused financial loss |
| IT service provider | Damage to client property while installing equipment on site | Client alleges system advice, configuration or implementation caused business loss |
| Bookkeeper | Visitor injury at a home office or business premises | Client alleges errors or omissions in bookkeeping work caused financial loss or penalties |
| Marketing agency | Injury at an event or damage while working at a client location | Client alleges campaign advice, content or strategy caused financial or reputational loss |
These examples are illustrative only. Whether a claim is covered depends on the policy wording, facts, exclusions, limits and insurer assessment.
What each policy may not cover
One common mistake is assuming that either type of policy covers every liability claim. In practice, liability policies contain definitions, exclusions, conditions, limits and excesses.
Public liability may not cover
- injuries to employees, which are usually dealt with under workers compensation arrangements;
- professional advice errors or poor professional recommendations;
- intentional or dishonest acts;
- contractual liabilities you accepted beyond normal legal liability;
- damage to your own property;
- some product-related claims unless product liability is included;
- events, locations or activities not disclosed to the insurer.
Professional indemnity may not cover
- general public injury or property damage unrelated to professional services;
- known circumstances that should have been disclosed before cover started;
- intentional, fraudulent or dishonest conduct;
- contractual penalties or guarantees outside the policy scope;
- unpaid fees or ordinary commercial disputes;
- work outside the professional services described in the policy;
- claims arising before the retroactive date, if one applies.
Before buying or renewing either cover, review the Product Disclosure Statement, policy schedule and wording. Pay close attention to what your business activities are described as, because a mismatch between your actual work and the insured business description can create problems at claim time.
How cover limits and costs are assessed
Insurers may consider different factors when setting premiums, excesses and cover terms. No article can tell you the exact cost or level of cover your business should choose, because this depends on your industry, activities, contracts and risk profile.
Factors that may influence public liability insurance include:
- your industry and occupation;
- whether customers or the public visit your premises;
- whether you work at client sites or in public spaces;
- the number of locations, employees or subcontractors;
- your annual turnover or business size;
- past claims history;
- the limit of indemnity and excess selected;
- any higher-risk activities, products or events.
Factors that may influence professional indemnity insurance include:
- the nature of your advice or professional services;
- your qualifications, experience and professional memberships;
- client types and contract values;
- whether you work in regulated or high-consequence fields;
- your annual fees or turnover;
- past claims or notified circumstances;
- the limit of indemnity, excess, retroactive date and extensions selected;
- whether you use subcontractors or outsource work.
When considering broader business insurance cover, it can be useful to compare how each policy responds to your actual client interactions, work activities and contractual obligations rather than focusing only on premium.
How to compare public liability and professional indemnity policies
When comparing public liability insurance Australia options or professional indemnity insurance Australia options, price is only one part of the assessment. A cheaper policy may not be suitable if it excludes the activities or claim types that matter most to your business.
Useful questions to ask include:
- Does the policy accurately describe all business activities, services and locations?
- Are subcontractors, labour hire workers or contractors treated clearly?
- What limit of indemnity is required by contracts, leases, licences or professional bodies?
- What excess applies to each type of claim?
- Are legal defence costs included within the limit or in addition to it?
- What exclusions apply to the work you actually perform?
- For professional indemnity, what is the retroactive date and is run-off cover available if needed?
- What notification obligations apply if you become aware of a potential claim?
If you are unsure how policy terms apply to your business, you may wish to speak with a licensed insurance broker. A broker can help explain options and obtain quotes, although any recommendation should still be assessed against your own circumstances and the policy documents. You can also learn more about available support through the business insurance brokers page.
What to do if an incident or potential claim occurs
If something happens that could lead to a claim, act promptly. Delay can create issues, especially for professional indemnity policies where notification obligations can be important.
General steps may include:
- Take reasonable steps to prevent further injury, damage or loss.
- Record what happened, including dates, times, people involved and relevant documents.
- Keep copies of emails, contracts, photos, reports, invoices or correspondence.
- Do not admit liability or agree to pay compensation without insurer guidance.
- Notify your insurer or broker as soon as practicable.
- Follow the claims process set out in your policy documents.
For more general background on business insurance types, you may also find the guide to business insurance for SME owners useful.
Key takeaway
Public liability and professional indemnity insurance protect against different liability risks. Public liability is generally about third-party injury or property damage connected to business activities. Professional indemnity is generally about client financial loss arising from professional advice, services, errors or omissions.
Some businesses may only need to focus heavily on one type of cover, while others may need both. The right approach depends on what your business does, where it operates, who relies on your work, your contracts and the insurer's policy terms. Reading the policy wording and asking targeted questions before buying can help reduce the risk of discovering a gap only after a claim arises.