If your loan application is declined because of your credit score
A credit score is one way lenders assess how likely a borrower is to repay money they borrow. If a lender declines your application because of your credit score, it does not mean you have no options, but it does mean you should pause before applying again.
Repeated credit applications can create additional enquiries on your credit file. Instead of immediately submitting another application, it is usually more useful to understand why the application was declined, check whether your credit report is accurate and address the factors that may have affected the lender's decision.
How credit scores affect loan approval
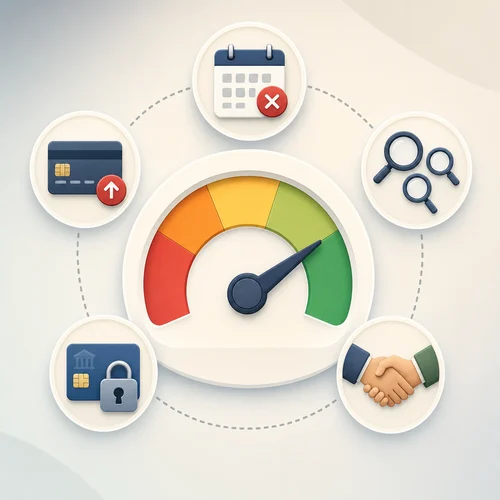
A credit score is a numerical representation of creditworthiness based on information in your credit history. In Australia, some credit scoring models use a scale that can run from 0 to 1,200. The score may be influenced by factors such as repayment history, existing debts, the length of your credit history and recent credit applications.
Lenders use credit scores and credit reports to help assess risk. A higher score may support an application, while a lower score may limit available options or lead to higher borrowing costs. However, a credit score is not the only factor a lender may consider. Income, expenses, existing commitments, loan type and the lender's own criteria can also matter.
| Credit score range | How it is commonly described | Possible lending impact |
|---|---|---|
| Above 800 | Excellent | May support access to stronger loan terms, depending on the lender and application details. |
| 700 to 799 | Good | May be viewed favourably by many lenders, subject to other assessment criteria. |
| 500 to 699 | Fair | May reduce the number of suitable loan options or affect pricing. |
| Below 500 | Poor | May make approval more difficult and can increase borrowing costs where finance is available. |
Different loan types may also treat credit score information differently. Personal loans often rely heavily on creditworthiness. Mortgages may involve more stringent assessment. Car loans may be assessed differently again, depending on the lender, the borrower and whether the loan is secured.
Steps to take after a loan denial
- Review the lender's explanation. Start with any denial notice or explanation you receive. It may identify whether the issue related to your credit score, repayment history, existing debt, income, affordability or another factor.
- Ask the lender for more detail. If the explanation is unclear, contact the lender and ask which parts of the application affected the outcome. Understanding the lender's criteria can help you decide what to address before applying elsewhere.
- Get a copy of your credit report. In Australia, you can request a free credit report each year from the main credit reporting agencies: Equifax, Experian and illion. Reviewing your report helps you see what lenders may be seeing.
- Check for incorrect information. Look for errors such as incorrect personal details, accounts you do not recognise, wrongly recorded missed payments or outdated information.
- Dispute errors promptly. If you find inaccurate information, follow the relevant credit reporting agency's dispute process. Correcting errors can help ensure your report accurately reflects your credit history.
How to improve your credit score before applying again
Pay bills and loan repayments on time
Payment history is an important part of credit assessment. Paying bills, credit cards and loan repayments on time can help protect your credit profile. Reminders or automated payments may help reduce the risk of missed due dates.
Reduce existing debt where possible
Existing debts can affect both your credit score and a lender's view of affordability. Reducing balances, particularly high credit card balances, may improve your position over time. The original article suggested aiming to use less than 30% of available credit limits as a practical benchmark.
Keep credit card balances manageable
High credit card balances can weigh against your credit profile. Paying balances down, and paying them in full where possible, may help show responsible credit management.
Limit unnecessary new credit applications
Each application for credit may result in a credit enquiry. Multiple enquiries in a short period can make an application look riskier to some lenders. If you are not ready to apply, consider researching criteria and checking your credit report first.
Monitor your credit report
Regularly checking your credit report can help you identify errors or negative marks that need attention. It can also help you understand whether your credit habits are moving in the right direction.
Consider the affordability of any future loan
Before applying again, it can be useful to estimate repayments under different loan amounts and terms. A personal loan repayment calculator can help you understand how repayments may fit into a budget, although it does not determine whether a lender will approve an application.
Thinking about another loan application
Once you understand why the application was declined, you can decide whether it makes sense to apply again immediately or spend time improving your credit position first. If your credit report contains errors, resolve them before submitting another application. If the issue is missed payments or high balances, improvement may take time and consistency.
If you want to research options without creating unnecessary credit enquiries, learn how soft credit checks may be used when comparing some loan options. Soft checks are different from formal hard enquiries, but borrowers should still read each lender's process carefully.
If you decide to compare available personal loan options, focus on the full terms, fees, repayment schedule and eligibility criteria rather than only the advertised rate or speed of application.
Alternative loan options to understand
If a traditional loan is declined because of your credit score, there may be other types of lending to consider. These options can involve different costs, criteria and risks, so it is important to understand how each works before applying.
Secured loans
A secured loan requires collateral, such as a car or another eligible asset. Because the loan is supported by collateral, the lender's risk may be lower than with an unsecured loan. This can affect how the application is assessed, but approval is not guaranteed.
Unsecured loans
An unsecured loan does not require collateral. The lender relies more heavily on creditworthiness, income, expenses and repayment capacity. If your credit score is low, unsecured loans may be harder to access or may involve higher borrowing costs.
Credit unions and community banks
Credit unions and community banks may apply different lending criteria from larger institutions. If you already have a relationship with one, it may be worth asking how they assess applications from borrowers with weaker credit histories.
Online lenders
Online lenders can offer digital application processes and faster decisions. Some focus on borrowers with less-than-perfect credit, but terms can vary widely. Read the loan contract, fees, interest rate and repayment requirements before proceeding.
Peer-to-peer lending
Peer-to-peer lending platforms connect borrowers with individual investors who fund loans. Criteria and pricing can differ from traditional lenders. As with any borrowing option, review the terms carefully and consider whether repayments are manageable.
No-credit-check style assessments
Some borrowers look for lenders that assess applications without relying only on a traditional credit score. These products still involve assessment and may consider other information about income, expenses and repayment capacity. You can read more about no-credit-check loan assessments before deciding whether this type of option is relevant to your situation.
Longer-term credit habits
Improving a credit score usually takes time. The most useful habits are consistent: pay obligations on time, reduce unnecessary debt, keep credit card balances under control, avoid repeated credit applications and check your credit report for accuracy.
A loan denial can feel discouraging, but it can also highlight what to improve before you approach another lender. Taking time to understand the reason for the decline and strengthen your credit profile may put you in a better position for future credit decisions, without guaranteeing any particular outcome.