What are car loan criteria?
Car loan criteria are the requirements and assessment factors a lender uses when reviewing a finance application. They help the lender estimate the risk of lending money to a borrower and decide whether the proposed loan appears manageable based on the information supplied.
Criteria vary between lenders, but Australian car loan applications are commonly assessed against a mix of borrower, loan and vehicle factors. This guide focuses on borrower eligibility and high-level approval criteria, including credit history, income, employment, debt-to-income ratio, deposit, requested loan amount, lender types, common application mistakes and what to do if an application is declined.
Common criteria lenders consider
While each lender applies its own policies, the following factors are commonly reviewed during a car loan assessment.
| Criteria | What it helps lenders assess |
|---|---|
| Credit score and credit history | How you have managed previous credit, loans and repayments. |
| Income | Whether you appear to have enough income to support the proposed repayments. |
| Employment stability | How consistent and verifiable your source of income appears to be. |
| Debt-to-income ratio | How much of your income is already committed to debts and regular obligations. |
| Deposit or down payment | Whether you can reduce the amount borrowed and demonstrate savings capacity. |
| Loan amount and loan term | Whether the requested finance is reasonable for your financial position. |
| Vehicle value and collateral | Whether the vehicle provides suitable security for the proposed loan. |
| Residency and documentation | Whether you meet the lender's identity, residency and evidence requirements. |
Credit score and credit history
Your credit score is a numerical indication of creditworthiness based on your credit history. Lenders use it, together with the detail in your credit file, to assess how you have handled debts in the past.
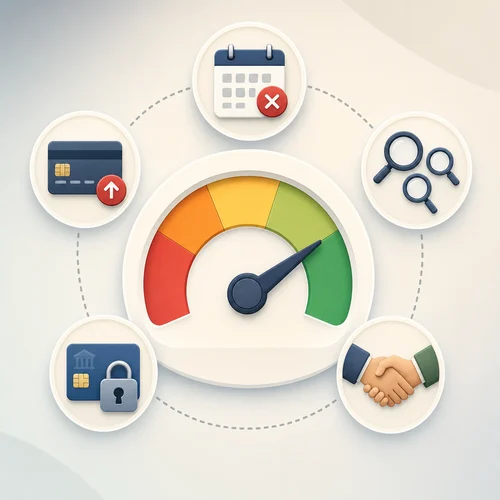
A credit history may include previous loans, credit card accounts, repayment behaviour, missed payments and other credit activity. A record of making payments on time and keeping debt levels manageable can support an application. A history of missed payments, high balances or repeated credit applications may make a lender more cautious.
Ways to strengthen your credit profile before applying
- Make bills, loan repayments and credit card payments on time.
- Reduce outstanding debts where possible.
- Avoid opening multiple new credit accounts in a short period.
- Keep longer-standing credit accounts in good order, as a longer credit history may be useful.
- Check your credit report and dispute any inaccuracies you identify.
Credit history is only one part of the assessment. A lender will usually consider it alongside income, employment, debts, the requested loan amount and other application details.
Income and employment stability
Income is central to car loan eligibility because lenders need to assess whether proposed repayments appear affordable. Applicants are commonly asked to provide evidence of income, such as recent payslips, employment details or other documents requested by the lender.
Employment history can also matter. A consistent employment record may indicate a more reliable income stream. Frequent job changes or periods without income may prompt a lender to request more information or assess the application more conservatively.
Self-employed applicants
Self-employed applicants may need to provide additional evidence because their income can vary. Documents may include tax returns, financial statements or other records that help show income stability over time. The exact requirements depend on the lender and the type of application.
Debt-to-income ratio
Debt-to-income ratio, often called DTI, is a measure of how much of your income is already committed to debt repayments and regular financial obligations. Lenders use it to help assess whether taking on another repayment may create repayment pressure.
A simple way to calculate DTI is to divide total monthly debt repayments by gross monthly income, then multiply the result by 100 to express it as a percentage.
- Add up monthly debt repayments, such as mortgage or rent commitments, credit card repayments, personal loans, student loans and other recurring debt obligations.
- Work out gross monthly income before tax and deductions.
- Divide the monthly debt figure by gross monthly income.
- Multiply by 100.
For example, if monthly debt repayments are $2,500 and gross monthly income is $7,000, the calculation is: ($2,500 / $7,000) x 100 = 35.7%.
A lower DTI may suggest more capacity to manage a new car loan repayment. A higher DTI may indicate that much of the applicant's income is already committed, which can affect eligibility or loan terms.
Deposit, loan amount and loan term
A deposit, sometimes called a down payment, is the amount paid upfront towards the vehicle. A larger deposit reduces the amount that needs to be borrowed. This can lower the lender's exposure and may reduce the size of monthly repayments.
The requested loan amount is also assessed against income, existing debts, credit history and the value of the vehicle. If the requested amount appears high compared with the applicant's financial position, a lender may be less comfortable with the application.
Loan term is another part of the affordability picture. A longer term may reduce individual repayments but can increase the period over which interest is paid. A shorter term may involve higher repayments. Before applying, borrowers often benefit from testing repayment scenarios with a car loan repayment calculator so they can understand how the amount borrowed and loan term may affect repayments.
Saving for a larger deposit
- Use a dedicated savings account for vehicle purchase funds.
- Set a monthly savings target and automate transfers where practical.
- Review discretionary spending to identify areas to reduce costs.
- Consider whether extra income from additional work could help build savings faster.
- Revisit the budget regularly to keep the savings plan realistic.
Vehicle value and collateral
For many car loans, the vehicle being purchased acts as collateral. This means the lender has a security interest in the vehicle until the loan is repaid. If repayments are not made, the lender may be able to repossess the vehicle to recover losses.
Vehicle value can influence how much a lender is willing to lend and how the loan is structured. Lenders may consider the car's market value, age and condition at a high level when assessing the security. This guide does not go deeply into vehicle-specific rules, as those requirements can differ depending on whether the vehicle is new or used, bought from a dealer or privately, and whether there is finance owing on it. For more detail, see this separate guide on how the vehicle can affect car loan approval and loan terms.
Before committing to a purchase, it can be useful to research the vehicle's market value using recognised vehicle pricing resources, compare similar cars for sale and consider an independent appraisal where appropriate.
Types of lenders and how requirements can differ
Australian car loan applicants may encounter several types of lenders, including banks, credit unions and online lenders. Each lender has its own credit policies, documentation requirements and approach to risk.
- Banks: Traditional lenders may offer a range of loan products and may apply stricter criteria around credit history and financial stability.
- Credit unions: Member-owned institutions may offer competitive rates and a more personalised service model. Criteria still apply and will vary by lender.
- Online lenders: Online lenders may provide convenient application processes and may assess a range of credit profiles, but rates, fees and terms should be compared carefully.
When comparing lenders, look beyond the headline rate. Review the loan term, repayment flexibility, application fees, processing fees, early repayment conditions and the evidence required to support the application. If you are at the stage of comparing available options or requesting a quote, you can start from the site's car loan quote start page.
Common car loan application mistakes
Some application issues can reduce the chance of a smooth assessment or result in less favourable terms. Common mistakes include:
- Not checking credit history first: Errors or unresolved issues may not be discovered until the lender reviews the file.
- Applying without a clear budget: Without a repayment budget, applicants may request a loan amount that does not fit their broader financial position.
- Making multiple applications in a short period: Multiple applications can create hard enquiries on a credit report and may affect how lenders view the application.
- Underestimating existing commitments: Rent, mortgage payments, credit cards, personal loans and other recurring costs all affect borrowing capacity.
- Providing incomplete documents: Missing income evidence, employment details or identification can delay assessment.
- Ignoring fees and conditions: Application fees, processing fees, early repayment conditions and other charges can affect the overall cost of a loan.
How to prepare before applying
- Review your credit report and address obvious errors or issues.
- Prepare a realistic budget that includes current expenses and existing debts.
- Estimate repayments before choosing a loan amount.
- Gather income, employment and identity documents in advance.
- Compare lenders and loan terms before submitting applications.
What to do if a car loan application is rejected
A declined application does not mean every future application will be declined. It usually means the lender was not satisfied that the application met its criteria at that time.
If an application is rejected, start by asking for the reasons. Lenders should provide information that helps identify the issue, such as credit history, income evidence, existing debts, requested loan amount or missing documentation.
Possible next steps include:
- Paying down existing debts where possible.
- Making all repayments on time to strengthen credit history.
- Reducing credit card balances and other revolving debt.
- Saving a larger deposit to reduce the amount borrowed.
- Considering a smaller loan amount or a less expensive vehicle.
- Checking whether additional documentation could better support income or employment stability.
- Allowing time for financial improvements before reapplying.
For a more focused explanation of post-rejection steps, see this guide on what to do if your car loan application is denied.
Key takeaways
Car loan criteria are designed to help lenders assess whether an applicant can manage the proposed finance. The most common factors include credit history, income, employment stability, existing debt levels, loan amount, deposit, loan term and the vehicle's value as collateral.
Before applying, it is worth checking your credit report, preparing a clear budget, estimating repayments, gathering documents and comparing lender requirements. These steps do not guarantee approval, but they can help you submit a more complete and informed application.
Published: Sunday 10th November, 2024
Last updated: Wednesday 26th August, 2026