Understanding bad credit and personal loans
Bad credit generally refers to a low credit score or credit history that suggests past difficulty managing repayments. In Australia, some credit scoring systems use ranges up to 1200, and a lower score may make a borrower appear higher risk to lenders.
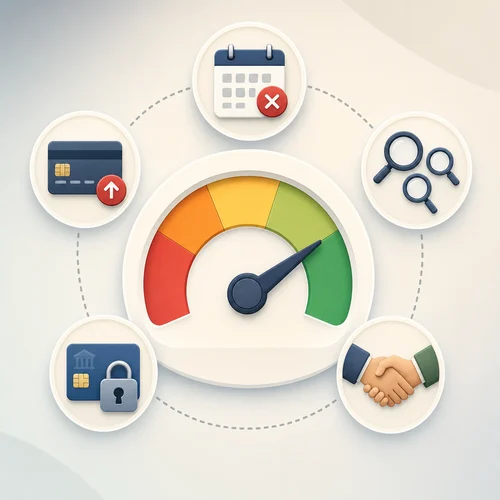
Credit scores are influenced by information in your credit history, including repayment patterns, existing debt levels, credit enquiries and the length of your credit history. Late or missed payments on bills, credit cards or loans can contribute to a lower score. So can high debt levels, frequent credit applications, a short credit history, bankruptcy or court judgments.
A lower credit score can affect access to personal loans and credit cards. Where credit is available, the loan may come with higher interest rates, fees or less favourable terms. That is why it is useful to understand both the application process and the total cost of borrowing before deciding whether to proceed.
Can you get a personal loan with bad credit?
Having bad credit can make approval more difficult, but some lenders assess more than the credit score alone. Depending on the lender and product, they may also consider your income, employment situation, expenses, existing debts and overall capacity to repay.
The Australian lending market includes banks, credit unions, online lenders, fintech platforms and specialist lenders. Some lenders focus on borrowers with less-than-perfect credit histories, while others have stricter credit requirements. This does not mean approval is guaranteed; it means lending criteria can vary and should be compared carefully.
If you decide to compare small loan options or begin an enquiry, focus on whether the loan amount, repayment term, fees and interest charges are manageable for your circumstances.
How to prepare for a faster small personal loan application
A faster application is usually helped by preparation. Before applying, it is worth checking what you can realistically afford and gathering the documents a lender is likely to request.
1. Review your financial position
Start by looking at your income, regular expenses and existing debts. This can help you decide whether borrowing is necessary, how much you may need, and whether repayments could fit into your budget without adding further pressure.
A repayment estimate can be useful when comparing loan amounts and terms. For example, a personal loan repayment calculator can help illustrate how loan size and term may affect regular repayments.
2. Check your credit report
Before making an application, review your credit report for errors or discrepancies. In Australia, credit reporting bodies include Equifax, Experian and illion. If you identify inaccurate information, you can raise a dispute with the relevant credit reporting agency.
An accurate credit report does not guarantee approval, but it helps ensure lenders are assessing the correct information.
3. Gather key documents
Having documents ready can reduce delays. A lender may ask for identification, proof of income, employment details and information about your expenses, debts and bank accounts. Requirements differ by lender, so check what is needed before submitting an application.
For more detail on typical borrower requirements, see this guide to eligibility for small loans under $10,000 in Australia.
4. Consider smaller loan amounts
Borrowing only what is needed can make repayments easier to manage and may reduce the lender's risk assessment. A smaller loan is not automatically easier to obtain, but requesting an amount that aligns with your income and expenses is a practical part of responsible borrowing.
5. Compare before applying
Each application can affect your credit file, so it is sensible to compare lenders, loan terms, fees and eligibility criteria before submitting multiple applications. Look at the total cost of the loan, not just the headline interest rate.
Loan options sometimes considered by borrowers with bad credit
Different loan structures may suit different circumstances. The options below are not recommendations, but they show how lenders may manage risk when assessing applications from borrowers with imperfect credit histories.
| Option | How it works | Points to compare |
|---|---|---|
| Specialist bad credit personal loan | Some lenders consider applicants with lower credit scores and may assess income and repayment capacity alongside credit history. | Interest rate, fees, repayment term, total cost and lender reputation. |
| Secured personal loan | The borrower provides collateral, which may reduce the lender's risk. | Whether you are comfortable using an asset as security and what happens if repayments are missed. |
| Co-signed loan | A co-signer with stronger credit may provide additional assurance to a lender, where this option is available. | The co-signer's responsibilities and the impact on both parties if repayments are not made. |
| Credit union or online lender | Some credit unions and online lenders may apply different criteria from traditional banks. | Eligibility rules, fees, customer service, transparency and loan terms. |
| Peer-to-peer lending platform | Some platforms connect borrowers with investors and may use different assessment methods. | Platform fees, rates, approval criteria and repayment conditions. |
Potential advantages and limitations
Possible access to funds
Some bad credit lenders use streamlined online processes, which may make applications and decisions faster than more traditional processes. Timing depends on the lender, the completeness of your application and whether further checks are required.
Opportunity to demonstrate repayment behaviour
If a loan is approved and repayments are made on time, responsible repayment behaviour may be reflected in your credit history over time. Missing repayments, however, can have the opposite effect.
Flexibility in loan structures
Some lenders offer different repayment terms or secured and unsecured options. Flexibility should be assessed against affordability, total cost and the consequences of missed payments.
Risks to watch before applying
Higher interest rates and fees
Loans for borrowers with bad credit may carry higher interest rates because lenders see a greater risk of non-repayment. Fees can also add to the total cost. Compare the interest rate, establishment fees, ongoing fees, late payment fees and the full repayment amount before deciding.
Predatory or unclear lending practices
Some lenders may use terms that are difficult to meet, hidden charges or aggressive marketing. Read the loan agreement carefully, ask questions about anything you do not understand and check whether the lender is licensed and transparent about costs.
Borrower protections, fees and responsible lending rules are important context when comparing small loans. You can read more in this guide to small loan regulations in Australia.
Over-borrowing
Borrowing more than you can repay can lead to ongoing financial stress and may create a cycle of debt. A budget can help you identify a manageable repayment amount and avoid taking on unnecessary debt.
Too many applications
Frequent credit enquiries can affect your credit file. Comparing options before applying may help you avoid submitting applications that do not match your circumstances or eligibility.
How to choose a reputable lender
When comparing lenders, look for clear information about interest rates, fees, repayment schedules and hardship processes. A reputable lender should provide transparent loan terms and explain what happens if repayments are late or missed.
Useful checks include:
- whether the lender clearly discloses rates, fees and repayment obligations;
- whether the lender explains eligibility criteria before you apply;
- whether the loan agreement is easy to understand;
- whether the lender appears to comply with Australian financial regulations;
- whether customer reviews and available information suggest reliable service; and
- whether the repayment amount is affordable based on your income and expenses.
Improving your credit position for future borrowing
Credit improvement is usually gradual. Consistent repayment behaviour and careful credit use can help strengthen your position over time.
Pay bills and loans on time
Late payments can negatively affect your credit score. Setting reminders or automatic payments may help reduce the chance of missing due dates.
Reduce existing debt where possible
High debt levels can affect how lenders view your capacity to take on new repayments. Paying down existing debts, especially higher-interest debts, may improve your overall financial position.
Monitor your credit report
Checking your credit report can help you identify errors and understand what lenders may see. If information is inaccurate, contact the relevant credit reporting agency to dispute it.
Use credit carefully
Avoid applying for new credit unnecessarily and try not to rely heavily on available credit limits. Keeping accounts in good standing can support a stronger credit profile over time.
Key takeaways
Bad credit can make personal loan applications more difficult, but some lenders consider broader financial information such as income, employment and repayment capacity. Preparing documents, reviewing your credit report and comparing the total cost of borrowing can help make the process clearer.
Before applying, focus on affordability, lender transparency and the risks of higher costs or over-borrowing. A small personal loan should be assessed as one part of your broader financial position, not as a guaranteed solution to financial stress.
Published: Wednesday 7th August, 2024
Last updated: Wednesday 26th August, 2026