Why your credit score matters before shopping for a car loan
A credit score is one of the tools lenders use to assess the risk of lending money. For car finance, it can influence whether an application progresses, what interest rate may be offered, how much flexibility is available in the loan terms and whether the lender requires stronger supporting information.
A higher credit score generally suggests a stronger repayment history and may support access to more favourable interest rates or loan conditions. A lower score does not automatically mean finance is unavailable, but it may lead to higher interest rates, stricter conditions or a narrower range of lenders willing to consider the application.
Understanding your credit score before you start comparing car finance can help you set realistic expectations, check for errors and prepare the information a lender is likely to request.
What is a credit score?
A credit score is a number based on information in your credit file. Credit reporting agencies calculate scores using details such as repayment history, credit accounts, loan and credit card applications, defaults, bankruptcies and other credit-related information.
Lenders use credit scores together with other information, such as income, expenses, employment, existing debts, the vehicle being financed and the proposed loan structure. A credit score is important, but it is not the only factor in a car loan assessment.
Credit score versus credit report
| Term | What it means |
|---|---|
| Credit report | A detailed record of your credit history, including credit accounts, repayment records, credit applications, defaults and other reportable credit events. |
| Credit score | A numerical summary derived from information in your credit report. It gives lenders a quick indication of how your credit history may be interpreted. |
Credit score ranges in Australia
In Australia, credit score ranges can differ between credit reporting agencies. Some scoring systems range from 0 to 1,200, while others range from 0 to 1,000. As a general guide, scores above about 620 are often considered fair, while scores around 700 and above are commonly treated as good, depending on the agency and lender.
Because each agency and lender may use different scoring and assessment methods, it is useful to treat your score as an indicator rather than a guaranteed outcome.
How lenders use credit scores for car loans
When assessing a car loan, lenders look at the likelihood that the borrower will repay the debt as agreed. A strong credit profile can suggest lower risk, while missed repayments, multiple recent applications or defaults may raise concerns.
Interest rates and loan terms
The interest rate offered on a car loan is often connected to the lender's risk assessment. A stronger credit score may support a lower rate, while a weaker score may result in a higher rate to reflect perceived risk. Over the life of a loan, a higher rate can increase the total amount paid in interest.
Credit history can also affect loan conditions, including the repayment period, the amount a lender is prepared to finance and whether additional requirements apply. For example, borrowers with stronger credit may receive more flexibility, while borrowers with lower scores may face stricter conditions.
Secured and unsecured car loans
A secured car loan usually uses the vehicle as security for the loan. This can reduce risk for the lender and may affect the rate or conditions offered. An unsecured loan does not use the vehicle as security and may come with higher interest rates because the lender has less protection if repayments are not made.
Your credit score can influence whether a lender is willing to offer secured or unsecured finance and on what terms. For more background on how vehicle security works, see this guide to secured car loans.
What can affect your credit score?
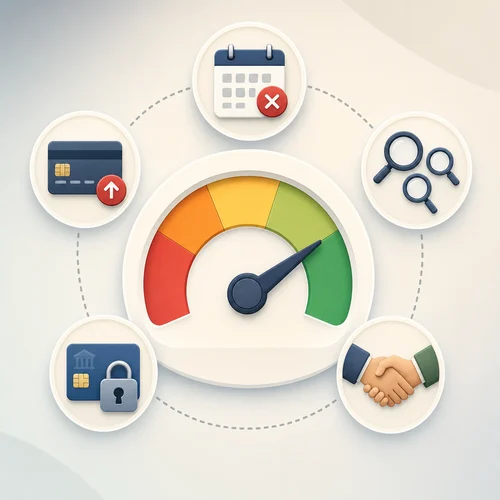
Credit scores can move up or down over time depending on how credit accounts are managed. Common factors include:
- Repayment history: Paying bills, credit cards and loans on time can support a stronger score. Late or missed payments can have a negative effect.
- Credit utilisation: Keeping credit card balances low compared with credit limits can be viewed more favourably than regularly using most or all available credit.
- Credit applications: Multiple applications for credit in a short period may negatively affect a score because each application can appear as an enquiry.
- Length of credit history: A longer history of well-managed credit can help demonstrate financial reliability.
- Types of credit used: Managing different types of credit responsibly may support a positive credit profile.
- Defaults, bankruptcies or serious credit events: These can significantly affect how lenders assess risk.
- Errors on the credit report: Incorrect listings, wrong personal details or unfamiliar debts may damage a score if they are not corrected.
How to check your credit score in Australia
Before applying for a car loan, it can be useful to check your credit score and review your credit report. Free credit score checks are available through a range of online providers, including services such as Credit Savvy, Finder and GetCreditScore, which may be connected with credit reporting agencies such as Experian or Equifax.
You will usually need to provide personal details and complete an identity check. Once you have access to your report, review it carefully for:
- incorrect personal details;
- credit accounts you do not recognise;
- repayments marked late when they were made on time;
- defaults or applications that appear incorrect; and
- signs of possible fraud or identity misuse.
If you find an error, contact the credit reporting agency to request a correction. An accurate credit report is important because the information in it can affect your score and how lenders view an application.
How often should you check?
Checking your credit score annually can help you stay aware of your credit position. If you are planning to apply for a car loan, checking a few months in advance may give you time to correct errors or improve your credit habits before applying. More frequent checks may be sensible if your financial circumstances change significantly or if you suspect fraudulent activity.
Ways to improve your credit score before applying
Improving a credit score usually involves consistent habits rather than quick fixes. Depending on your circumstances, the following steps may help strengthen your credit profile over time:
- Pay bills and loan repayments on time. Consistent repayment behaviour is one of the most important signals of reliability.
- Reduce credit card balances. Keeping balances well below credit limits can help reduce credit utilisation.
- Avoid unnecessary credit applications. Applying for several credit products in a short timeframe can create multiple enquiries on your report.
- Review and correct your credit report. Disputing incorrect information can prevent avoidable damage to your score.
- Manage existing debts carefully. A structured repayment plan can help reduce debt and improve overall financial stability.
- Consider whether debt consolidation is appropriate. Consolidating multiple debts into one repayment may simplify money management, but the full cost, rate, fees and loan term should be understood before proceeding.
Debt repayment strategies, such as prioritising higher-interest debts or following a structured repayment method, may also help reduce overall debt. The key is to use a plan that is realistic and sustainable.
What if you have a lower credit score?
A lower credit score can make car finance more challenging, but it does not necessarily remove all options. Some lenders specialise in assessing borrowers with adverse credit histories. These loans may involve higher interest rates or stricter conditions, so it is important to understand the total cost before committing.
Lenders may also consider supporting information such as stable income, employment history, existing financial commitments and the size of any deposit. Being transparent about your circumstances and the steps you are taking to improve your credit position can help a lender understand the application more clearly.
Be cautious with no credit check loans
Non-traditional options, including "no credit check" loans or payday-style lending, can appear convenient for people with poor credit. However, these products may involve high interest rates and fees. Before taking this path, read the terms carefully and consider whether the repayments are manageable.
If debt stress is already a concern, speaking with a financial counsellor may help you understand your options before taking on further credit.
How to compare car loan options
When choosing a car loan, avoid focusing only on the advertised interest rate. The real cost of finance can also depend on fees, loan term, repayment frequency, early repayment conditions and whether a balloon or residual payment applies.
Useful comparison points include:
- interest rate and comparison rate;
- application, account-keeping and early repayment fees;
- loan term and repayment frequency;
- whether the loan is secured or unsecured;
- whether extra repayments are allowed;
- any balloon or residual payment; and
- the total amount payable over the full term.
For a deeper explanation of loan pricing, see this guide on how to compare car loan rates, fees and total cost.
If you are ready to review current options, you can compare available car loan options while keeping your budget, credit profile and repayment capacity in mind.
Preparing for a car loan application
Good preparation can make the application process clearer and reduce delays. Lenders commonly ask for information and documents such as:
- proof of identity, such as a driver licence or passport;
- proof of income, such as recent payslips or tax returns;
- proof of residence, such as a utility bill or lease agreement;
- details of existing debts and living expenses;
- information about the vehicle being purchased; and
- visa documentation, where relevant for temporary residents.
Work out what repayments may look like
Before applying, compare possible repayment amounts under different loan terms and interest rates. A car loan repayment calculator can help estimate repayments and show how loan term and interest affect the total cost.
Understand pre-approval
Car loan pre-approval can give you an indication of how much a lender may be prepared to lend before you choose a vehicle. This can help with budgeting and may make the buying process more organised.
Pre-approval is usually conditional. It may be valid for a limited period, often around 30 to 60 days, and final approval depends on the lender verifying your documents, financial position and the vehicle details. It should not be treated as a guarantee of finance.
Common mistakes to avoid
When seeking a car loan, the following mistakes can create unnecessary cost or stress:
- Ignoring ownership costs: Budget for insurance, registration, maintenance and running costs as well as loan repayments.
- Borrowing more than is manageable: Compare income, expenses and existing debts before committing to repayments.
- Not checking your credit report: Errors or outdated information can affect the lender's assessment.
- Applying with multiple lenders at once: Several credit enquiries in a short period can affect your score.
- Focusing only on the lowest repayment: A longer term may reduce monthly repayments but can increase total interest paid.
- Overlooking fees and conditions: Application fees, account fees and early repayment penalties can affect the true cost.
- Assuming pre-approval is final approval: Final approval still depends on lender checks and documentation.
Key takeaways
Your credit score can influence car loan options in Australia, but it is only one part of a lender's assessment. Income, expenses, existing debts, employment, the vehicle and the loan structure also matter.
Before applying, check your credit report, correct any errors, understand your budget and compare the full cost of different loans. If your score is lower than expected, improving repayment habits and reducing debt may help strengthen your position over time.