Liability insurance policies do not all respond to claims in the same way. Two common policy triggers are claims-made insurance and occurrence-based insurance. The difference matters because it can affect whether a claim is considered under the policy you hold now, the policy you held when the work was done, or a policy you no longer have.
For Australian business owners, contractors, consultants and professionals, this is more than technical wording. It can influence how you renew cover, notify potential issues, change insurers, close a business, retire from practice or respond to client contract requirements. This guide explains claims-made vs occurrence liability insurance in practical terms, including retroactive dates, notification timing and run-off cover.
The short answer: what is the difference?
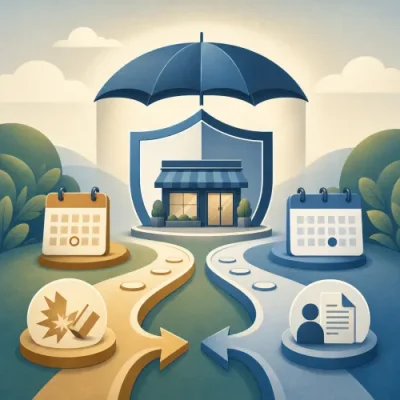
An occurrence-based liability policy is generally triggered by when the incident occurred. A claims-made liability policy is generally triggered by when the claim is first made against you and notified to the insurer, subject to the policy terms.
| Feature | Occurrence-based cover | Claims-made cover |
|---|---|---|
| Main trigger | The incident, injury, damage or event occurs during the policy period. | The claim is first made against you and notified during the policy period. |
| Common examples | Public liability insurance is often arranged on this basis, depending on the policy wording. | Professional indemnity insurance is commonly arranged on this basis. |
| Why timing matters | The key question is usually when the relevant event happened. | The key questions usually include when the work occurred, when the claim was made, when it was notified and whether the retroactive date applies. |
| After policy expiry | A later claim may still relate back to a covered event during the policy period, subject to terms and exclusions. | If the policy has ended, a later claim may not be covered unless there is appropriate continuing cover, such as run-off cover, or another applicable arrangement. |
These descriptions are general only. The actual outcome depends on the specific policy wording, exclusions, limits, notification conditions and insurer assessment.
How occurrence-based liability insurance works
Occurrence-based insurance focuses on when the event happened. If an incident occurs during the policy period, the policy may respond even if the claim is made later, provided the claim otherwise meets the policy terms.
For example, suppose a customer slips at a business premises during the period when a public liability policy is active. If the customer makes a claim after that policy period has ended, the relevant occurrence may still be the slip incident that happened while the policy was in force. The insurer would then consider the claim under the policy terms that applied at the time of the incident.
This is why occurrence-based cover can be important for risks involving a physical incident, such as third-party injury or property damage. However, it does not mean every later claim will automatically be accepted. Insurers will still review the facts, exclusions, policy limits, evidence and whether the claim falls within the insured activities.
How claims-made insurance works
Claims-made insurance focuses on when the claim is first made against the insured and when it is notified to the insurer. It is commonly used for professional indemnity insurance and some other liability covers where the alleged error, advice, omission or breach may not be discovered until months or years after the work was performed.
Under a claims-made policy, it is not enough that the work was performed during a period when you had insurance. A claim generally needs to be made and notified during the current policy period, subject to any retroactive date and other policy conditions.
For example, a consultant may complete a project in one year, but the client may not allege a professional error until a later year. The policy that may be relevant is often the one in place when the claim is first made and notified, not necessarily the one held when the original work was performed. The insurer will also consider whether the alleged act falls after the policy’s retroactive date.
If you are comparing types of business liability cover, it can help to understand the broader differences between covers. The guide to types of liability insurance in Australia explains how public liability, professional indemnity and product liability insurance commonly differ.
Why claims-made vs occurrence liability insurance matters
The policy trigger can affect several practical decisions for a business or professional. In particular, it can influence how carefully you manage renewals, claims notifications and changes in cover.
1. A gap in cover can have different consequences
With a claims-made policy, maintaining continuous cover can be especially important. If a policy lapses and a claim is first made during the gap, there may be no active policy to notify. Even if the underlying work happened while you previously had insurance, the expired policy may not respond if the claim was not made and notified during that policy period.
With occurrence-based cover, a gap may still create risk for incidents that happen during the uninsured period. However, the timing issue is different because the key event is usually the occurrence itself.
2. Switching insurers needs careful handling
When changing from one claims-made policy to another, you should review continuity of cover, retroactive dates, known circumstances and any policy conditions about prior matters. If you know about a circumstance that could lead to a claim, it may need to be notified to the current insurer before changing policies, depending on the wording.
Failing to disclose or notify a known issue can create problems later. The outgoing insurer may say it was not notified during the policy period, while the new insurer may exclude prior known circumstances. The exact position depends on the policy wording and the facts.
3. Policy documents may look similar but operate differently
Two liability policies can have similar limits, excesses and premiums but very different triggers. Reading only the premium and sum insured is not enough. You need to understand whether the policy is claims-made, occurrence-based or uses another form of trigger.
What is a retroactive date in insurance?
A retroactive date is particularly important in claims-made insurance. It is the date from which the policy may consider prior acts, errors or omissions, subject to the policy wording. If the alleged wrongful act occurred before the retroactive date, the policy may not respond even if the claim is made during the current policy period.
For example, a professional indemnity policy might have a retroactive date that matches the date the insured first took out continuous cover. If the professional later receives a claim about work done after that date, the current policy may consider it. If the work occurred before that date, cover may be limited or excluded.
Some policies may show an unlimited retroactive date, while others may use a specific date. Do not assume a retroactive date is favourable without checking the policy schedule and wording. If you change insurers, it is important to check whether the new policy preserves your previous retroactive date where appropriate.
What is run-off cover?
Run-off cover is a form of continuing claims-made cover for work performed in the past. It is commonly discussed in professional indemnity contexts when a business closes, a professional retires, a contractor stops offering certain services, or a company is sold or restructured.
Because professional claims can arise after the work is completed, ending a claims-made policy can leave past work exposed if a claim is made later. Run-off cover may allow claims made after the business has ceased or changed to be notified under continuing insurance, subject to the run-off terms.
Run-off needs can vary significantly by profession, contract, industry body, licensing requirement and insurer. Some professions or contracts may require a certain period of run-off, but there is no single rule that applies to every Australian business. If you are arranging professional indemnity insurance, the guide to professional indemnity insurance in Australia provides more context on how this cover is commonly used.
Common situations where timing can create problems
Claims-made and occurrence-based policy triggers often become important when something changes. Common situations include:
- Renewal delays: a business misses a renewal date and a claim or incident occurs during the gap.
- Changing insurers: a new claims-made policy has a different retroactive date or excludes known circumstances.
- Business closure: a consultant stops trading but later receives a complaint about earlier work.
- New contracts: a client requires evidence of cover but the policy type does not match the contractual risk.
- Late notification: a potential claim is not reported promptly, even though the policy requires notification as soon as practicable.
- Entity changes: a sole trader incorporates, restructures or sells a business and does not check whether prior work remains covered.
What should you check in your policy wording?
Before buying, renewing or changing liability insurance, read the policy schedule and wording carefully. If you are unsure, ask the insurer or a qualified insurance broker to explain how the policy trigger works for your circumstances.
Key items to check include:
- whether the policy is claims-made, occurrence-based or another structure;
- the policy period and when notification must be given;
- any retroactive date and how it affects past work;
- requirements for notifying claims, complaints or circumstances that may give rise to a claim;
- exclusions for known circumstances, prior claims or prior matters;
- how the policy responds if you change insurer at renewal;
- whether run-off cover is available or required if you stop trading, retire or sell the business;
- the insured business activities, named insured entities and professional services description;
- limits, excesses and any sub-limits relevant to your risk.
If you need help reviewing wording or comparing policy options, the brokers page may be a useful starting point for finding assistance. Any policy recommendation should take account of your business activities, contracts, claims history and insurer criteria.
Practical examples
Example 1: Public liability incident reported later
A trades business has public liability insurance for the year. During that year, a visitor alleges they were injured because of the business’s worksite activity. The visitor does not formally pursue the matter until after the policy has renewed. If the policy is occurrence-based, the insurer may look at when the injury occurred and assess the claim under the policy that was active at that time, subject to the policy wording.
Example 2: Professional complaint after a project ends
A consultant provides advice in one year. Two years later, the client alleges the advice caused a financial loss. If the consultant’s professional indemnity policy is claims-made, the relevant policy may be the one in force when the claim is first made and notified, provided the work is after the retroactive date and no exclusion applies.
Example 3: Business closes without run-off cover
A professional closes their practice and cancels their claims-made professional indemnity insurance. A former client later makes a claim about advice provided before closure. Without run-off cover or another applicable arrangement, there may be no current claims-made policy to notify. This is why closing or selling a professional services business should include an insurance review.
Questions to ask before choosing or renewing liability cover
When comparing claims made vs occurrence liability insurance, consider asking:
- What event triggers this policy?
- If a claim is made next year about work done this year, which policy would respond?
- What is the retroactive date, and does it preserve my previous cover history?
- What must I notify before renewal or before switching insurers?
- Does the policy exclude known circumstances or prior matters?
- What happens if I stop trading, retire or sell the business?
- Is run-off cover available, and what period may be appropriate?
- Do my client contracts, licence conditions or professional obligations require a particular type of cover?
Final Thoughts
Claims-made and occurrence-based liability insurance are not interchangeable. Occurrence-based cover generally looks at when the incident happened. Claims-made cover generally looks at when the claim is made and notified, while also considering matters such as retroactive dates and prior known circumstances.
For public liability risks, occurrence-based wording is common, but you should still check the policy. For professional indemnity and other professional liability risks, claims-made wording is common, making continuous cover, timely notification and run-off planning especially important.
The safest approach is to review the policy trigger before you buy, renew, switch insurers or close a business. The right structure and terms depend on your business activities, professional obligations, contracts, claims history and insurer requirements.