
Smartraveller updated its guidance on 1 October 2026, warning that complimentary travel insurance attached to existing credit cards may also be affected. That is important because many travellers think of card cover as a standing benefit: once used, always available. In practice, the current product disclosure statement, eligibility rules and effective dates are what matter.
Industry reporting has linked the broader shift to changing credit card economics ahead of payment reforms, while also noting that individual bank decisions and insurer arrangements vary. The practical result for travellers is the same: some cards have lost cover altogether, while others have shorter maximum trip periods, reduced benefits or new activation steps. Areas commonly worth checking include medical expenses, cancellation, travel delay, luggage, rental vehicle excess, excess amounts and whether family members are included.
The timing is awkward for Australians planning Christmas, New Year and 2027 travel. A trip booked months ago may sit across old and new policy dates, and the answer may depend on when the cover was activated, when the trip was paid for, the card used and when the claimable event occurs. Travellers should not assume that paying for flights on a card is enough unless the current terms say so.
This is also a reminder that complimentary credit card travel insurance is not automatically equivalent to a standalone policy. Card-linked cover can be useful, especially for eligible travellers who understand the conditions, but it may have stricter activation requirements, limited pre-existing medical condition treatment, narrower cancellation benefits or exclusions that only become obvious at claim time.
A sensible review is less about finding the cheapest alternative and more about matching the cover to the trip. Travellers may wish to check:
- whether the card still includes domestic or international travel insurance;
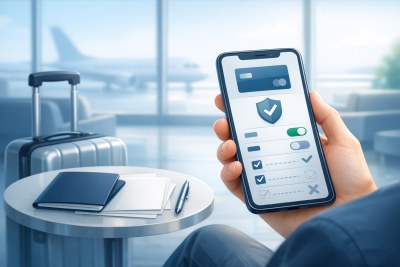
- the exact activation steps and any minimum spend requirement;
- the maximum trip length and destination limits;
- whether cancellation, luggage and delay benefits remain included;
- how pre-existing medical conditions, adventure activities and cruises are treated;
- which excess applies to each claim type.
For anyone comparing policies, the same discipline applies beyond credit cards: read the wording, understand the exclusions and keep records of activation, bookings and payments. General guides such as What Does Travel Insurance Cover? can help frame the questions, but the final answer always sits in the current policy documents for the specific cover being relied upon.
Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.