The concern is that inflation in repairs, replacement technology, building materials, labour and logistics can quietly outpace the figures listed on a policy schedule. A freelancer who set cover levels several years ago may assume they are protected, only to find that the insured amount falls short after theft, fire, storm damage or another insured event. That gap can become a direct cash flow problem at the worst possible moment.
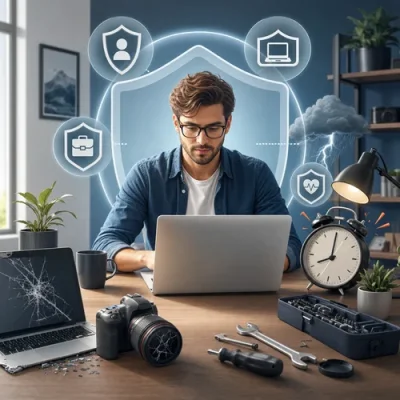
Underinsurance also interacts with interruption risk. If a designer, photographer, consultant or trades-based contractor cannot work while equipment is replaced or a workspace is repaired, the issue is not only the cost of the damaged asset. It is also missed deadlines, lost billable hours and the potential strain on client relationships. That is where business interruption insurance may become relevant, particularly for freelancers whose income depends on specific tools, premises or project timelines.
A practical review does not need to be complicated, but it should be specific. Freelancers should avoid relying only on accounting book values, because depreciated figures may be far below today's replacement cost. Instead, consider what it would cost to buy equivalent equipment now, restore essential files or systems, replace furnishings, meet lease or studio obligations, and keep the business operating during a disruption.
Useful checkpoints include:
- Reviewing policy schedules before renewal, not after a claim.
- Checking whether portable equipment is covered away from the main premises.
- Testing whether business interruption limits reflect current revenue and recovery time.
- Keeping receipts, asset registers and photographs in secure cloud storage.
- Confirming whether exclusions, sub-limits or excesses could reduce the expected payout.
The broader lesson is that affordability should not be measured by premium alone. A cheaper policy with outdated limits may leave a freelancer funding the difference personally. For self-employed Australians without paid leave or employer support, estimating replacement costs and interruption exposure is part of protecting both today's work and tomorrow's earning capacity.
Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.